




 23








- My Forums
- Tiger Rant
- LSU Recruiting
- SEC Rant
- Saints Talk
- Pelicans Talk
- More Sports Board
- Fantasy Sports
- Golf Board
- Soccer Board
- O-T Lounge
- Tech Board
- Home/Garden Board
- Outdoor Board
- Health/Fitness Board
- Movie/TV Board
- Book Board
- Music Board
- Political Talk
- Money Talk
- Fark Board
- Gaming Board
- Travel Board
- Food/Drink Board
- Ticket Exchange
- TD Help Board
Customize My Forums- View All Forums
- Show Left Links
- Topic Sort Options
- Trending Topics
- Recent Topics
- Active Topics
Started By
Message
Credit Card Question
Posted on 10/28/26 at 7:40 pm
Posted on 10/28/26 at 7:40 pm
I've had the same credit card for 30+ years.
I've only ever had 1 credit card.
I put all my bills on this card and pay it off monthly.
I earn 1 point per dollar spent (1%) on everything and once every few years, I turn in those points for gift cards and buy something nice.
Obviously I'm leaving some rewards on the table.
What card should I go with for better rewards?
I don't travel so I'm not looking for airline miles or travel rewards.
I'm just looking for something simple.
Earn points (greater than 1%) and turn in for rewards every 2-3 years
No annual fee.
I think something like Chase Freedom may be something like what I need.
Posted on 10/28/26 at 7:41 pm to WM88
Slate
Posted on 10/28/26 at 7:41 pm to WM88
No wealthy person ever became that way off credit card perks
Posted on 10/28/26 at 7:42 pm to WM88
Chat gpt says: Honestly, I think you're a perfect candidate for a flat-rate 2% cash-back credit card. You already have the ideal credit-card habits: one card for your bills and everyday spending, paying the balance in full every month, and redeeming rewards for something nice every few years.
You don't need to juggle multiple cards, track rotating categories, or learn a complicated points system. You can keep doing exactly what you're doing now and simply double your rewards.
My top 3 cards for you
2% cash back on everything
$0 annual fee
This is the simplest upgrade. Every eligible purchase earns 2%, with no categories to activate and no spending caps on the base rewards. You can redeem cash rewards rather than deal with airline miles or travel portals. ?
2% cash back on everything
$0 annual fee
Another excellent fit. You earn 1% when you buy and another 1% when you pay for the purchase. Since you already pay your balance in full monthly, that structure should suit you well. Rewards can be redeemed for cash back. ?
1.5% base, 3% in select categories
$0 annual fee
If you like Chase's rewards program, this is the more straightforward Freedom card. It earns 3% on dining and drugstores, but only 1.5% on most other purchases. That means it may earn less overall than a flat 2% card if you put all your bills on it. ?
Posted on 10/28/26 at 7:47 pm to WM88
We have Chase plus a number of others. Apple Card is a good one too.
Chase:
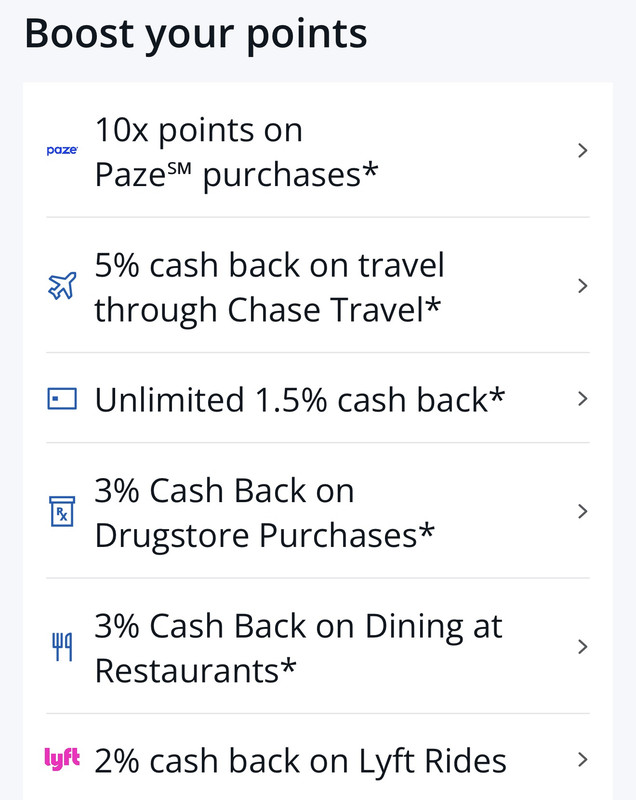
Chase:
This post was edited on 10/28/26 at 7:49 pm
Posted on 10/28/26 at 7:48 pm to WM88
Depends on your spending. Flat rate 2% cards will be tough to beat if you don't travel.
Chase ultimate rewards points are best used on travel.
Costco card with no annual fee is pretty solid as well
5% Costco gas
4% any gas
3% restaurants and travel
2% Costco purchases
1% anything else
They cut you a check once a year
Chase ultimate rewards points are best used on travel.
Costco card with no annual fee is pretty solid as well
5% Costco gas
4% any gas
3% restaurants and travel
2% Costco purchases
1% anything else
They cut you a check once a year
Posted on 10/28/26 at 7:48 pm to Keith13
quote:
No wealthy person ever became that way off credit card perks
No, but it does add up to a tidy amount over time.
1% over several years will be in the 1000s for most folks.
Posted on 10/28/26 at 7:49 pm to UltimaParadox
Cabelas.
- Silver status 3%
- Black 5%
Then you can buy all kinds of cool hunting, fishing and camping stuff!
- Silver status 3%
- Black 5%
Then you can buy all kinds of cool hunting, fishing and camping stuff!
This post was edited on 10/28/26 at 7:53 pm
Posted on 10/28/26 at 7:51 pm to WM88
You’re probably just leaving a percent on the table if you want to keep it simple and straightforward. So just get one of the 2% cash back or points cards. If you’re patient, they’ll have transfer bonus windows with hotel chains, airlines, etc. and you can capitalize and get 2.5% or something.
If you want to complicate it a little, you can probably string together 3-4 cards that have no annual fees that will pay you 3-5% back for gas, hotels, groceries, etc.
If you want to complicate it a little, you can probably string together 3-4 cards that have no annual fees that will pay you 3-5% back for gas, hotels, groceries, etc.
Posted on 10/28/26 at 7:54 pm to WM88
Stick with cash, especially if you pay in full every month
Rewards are overinflated to goods / services received, cash is cash
Posted on 10/28/26 at 7:57 pm to WM88
Thanks all.
I'm a little confused on the verbiage of "cash back".
To me that sounds like a discount or them sending me a check which is not what I'm looking for.
Is cash back just another term for reward points?
I'm a little confused on the verbiage of "cash back".
To me that sounds like a discount or them sending me a check which is not what I'm looking for.
Is cash back just another term for reward points?
Posted on 10/28/26 at 7:58 pm to Cheese Grits
quote:
Stick with cash, especially if you pay in full every month
Rewards are overinflated to goods / services received, cash is cash
Cash is leaving a lot of money on the table. Majority of business factor in the cost of the transaction fees into the price. Very little places to cash discount.
You are generally at a disadvantage paying cash. Not even factoring in the hassle of carrying cash.
If you are paying it off every month, card is king
Posted on 10/28/26 at 8:01 pm to Keith13
quote:
No wealthy person ever became that way off credit card perks
Most wealthy people have cards that cost $1k plus in annual fees

Posted on 10/28/26 at 8:01 pm to Cheese Grits
quote:
Stick with cash, especially if you pay in full every month Rewards are overinflated to goods / services received, cash is cash
What an idiot
Posted on 10/28/26 at 8:03 pm to WM88
I earn 6% back on my Bank of America rewards card in my category of choice. I think it's only for a year though.
Posted on 10/28/26 at 8:09 pm to Keith13
quote:
No wealthy person ever became that way off credit card perks
Sports betting gamblers do.
Posted on 10/28/26 at 8:26 pm to WM88
It depends a lot on your spending patterns. Nerdwallet is a good site for comparing lots of cards and their benefits.
If you spend money online regularly, consider getting a Capital One shopping account. It is free, and you don't have to use a Capital One card, and I regularly get large (10%+) offers. It is separate from your card account so it stacks. I have gotten $1477 back in the last ~18 months. The bonus cash back is not "cash" but credit you can use for gift cards. There lot of participating companies offering gift cards but we use most of them for Chewy and Petco.
If you spend money online regularly, consider getting a Capital One shopping account. It is free, and you don't have to use a Capital One card, and I regularly get large (10%+) offers. It is separate from your card account so it stacks. I have gotten $1477 back in the last ~18 months. The bonus cash back is not "cash" but credit you can use for gift cards. There lot of participating companies offering gift cards but we use most of them for Chewy and Petco.
Posted on 10/28/26 at 8:52 pm to Obtuse1
I don’t have time to worry about this nickel and dime BS.
Flat % back. Paid off every month.
Flat % back. Paid off every month.
Posted on 10/28/26 at 8:58 pm to UltimaParadox
quote:
Not even factoring in the hassle of carrying cash.
Lord, it is SO much of a hassle by having a couple of hundred bucks in cash with me. It must weigh upwards of 10 freaking grams....
Ohhhh, my backkkk!
Posted on 10/28/26 at 9:15 pm to WM88
Chase had a card for you like 20 years ago, but they have discontinued it. If they still have Signature cards in their Freedom line, look into it.
I think my interest rate from then was locked in at 3 to 6 percent (which is why they want customers to swap out). Now I think that rate is more like 9 to 12 percent. Dropped mine around start of c19 (like I need a credit card at my age).
The signature part got you perks on reservations and sports events.
 Page 1 of 3

Popular
Back to top
 Follow TigerDroppings for LSU Football News