




 0





- My Forums
- Tiger Rant
- LSU Recruiting
- SEC Rant
- Saints Talk
- Pelicans Talk
- More Sports Board
- Fantasy Sports
- Golf Board
- Soccer Board
- O-T Lounge
- Tech Board
- Home/Garden Board
- Outdoor Board
- Health/Fitness Board
- Movie/TV Board
- Book Board
- Music Board
- Political Talk
- Money Talk
- Fark Board
- Gaming Board
- Travel Board
- Food/Drink Board
- Ticket Exchange
- TD Help Board
Customize My Forums- View All Forums
- Show Left Links
- Topic Sort Options
- Trending Topics
- Recent Topics
- Active Topics
Started By
Message
Posted on 10/22/26 at 8:55 am to stout
Our neighborhood has homes from 400k to over a million. For the last several years there were never more than maybe half a dozen for sale because they snapped up so quickly by buyers. Average number of days on the market was around 3 for years. Now we have 20 houses on the market and they arent selling at all. Many have been listed for months. So the inventory is there but the buyers are no longer interested, starting basically just within the last 3 months or so. Seems like theres a pretty clear correlation to the rates increasing to a point buyers just arent willing to pay.
This post was edited on 10/22/26 at 8:56 am
Posted on 10/22/26 at 8:55 am to Henry Jones Jr
quote:
Sounds like buyers will eventually have to realize they don’t control the price. The sellers do.
Sellers don't control the price any more than the buyers. Buyers have to be able to qualify for a loan as well as the costs for insurance, repair, taxes, etc
When it is significantly cheaper to rent than buy people won't buy as frequently - unless you are the type of buyer immune to price (tech millionaires for example). That is reflected in the transaction numbers (which have been extremely low for more than 3 years - because buyers CAN'T afford to buy in most cases.
Foreclosures have been essentially stopped by government intervention since 2019. Those will come increasingly to market over the next 12 months.
Unless the seller is a wealthy person totally immune to price point the sellers also couldn't afford the home they bought at a sub 3% interest rate loan.
Posted on 10/22/26 at 9:00 am to TideSaint
quote:
Developers continuing to build new neighborhoods with 1,500 homes and agreeing to buy down points isn't helping, either.
New home starts are way down and one of the largest builders in America, Lennar, is allegedly colluding with another entity they have an interest in, buying their own homes and renting them for less than market value in order to keep their sales comps and stock prices propped up
The US housing market just took a turn: Unusual home sales trigger alarm
Posted on 10/22/26 at 9:02 am to CatfishJohn
quote:
Because people don't want to sell their current homes with low rates and take on a much larger rate.
You 1000% misunderstood my post and just repeated what the previous person did.
Yes, people with 3% may not be willing to sell but there are sellers. We have the largest gap of sellers vs buyers in history, meaning that despite people with 3% mortgages not being willing to sell, there are still people trying to sell.
There are no buyers at current rates and prices. That's the issue
Posted on 10/22/26 at 9:04 am to Mahootney
quote:
A home is only worth what someone is willing to pay
and you're not the only buyer. This shite goes both ways. With every single commodity that is openly "traded" 'in a free market.
quote:
Yes, your home "was worth" $600k a couple of years ago.
But you built it for $60k in 1995.
WTF does this have to do with anything? The idea is to sell your product for the most money someone is willing to pay while keeping you cost as low as possible. The frick does his $60K 1995 cost have to do with today's asking price?

Get over the fact that it might be a "Boomer" owner or what they paid for it.
Posted on 10/22/26 at 9:04 am to stout
Where are we supposed to be in order to be in a "healthy" market. Homes selling too fast, people are here complaining and then others are saying "inventory levels are too low'.
Homes not selling fast enough, market sucks and interest rates are too high.
Looking at Stout's graph, outside of the major peaks of 2005-2008 and 2020-2022 the current market doesn't seem that off to me.
Its easy to skew the actual data with statistics.
I'm not convinced that 2005-2008 when a home across the street from me sold 3 times in one year, or 2020 when we had covid panic buying to move out of the city is really worth comparing a healthy market to.
Posted on 10/22/26 at 9:06 am to stout
quote:
You 1000% misunderstood my post and just repeated what the previous person did.
Yes, people with 3% may not be willing to sell but there are sellers. We have the largest gap of sellers vs buyers in history, meaning that despite people with 3% mortgages not being willing to sell, there are still people trying to sell.
There are no buyers at current rates and prices. That's the issue
You misunderstood my post.
A huge portion of potential buyers have been removed from the market because they don't want to sell their current homes with their current rates. I am one of those. I'd be in the market to buy a home, but I'm not because of rates of my current home.
If I was already at 6% or something, I'd buy a house yesterday.
ETA:
and anecdotally I have quite a few friends that are in the same boat.
This post was edited on 10/22/26 at 9:11 am
Posted on 10/22/26 at 9:08 am to stout
We’re still years away from adequate inventory.
Posted on 10/22/26 at 9:09 am to Jon Ham
quote:
It’s not life or death though
Forbearance applications took a huge jump in August as did preforeclosure activity AKA people in the 60-120 day late on their mortgage payments
The forbearance activity actually caused a dip in new foreclosures MoM for the first time in like 18 months.
quote:
Number of properties that are 30 or more days past due, but not in foreclosure: 1,956,000
Month-over-month change: 81,000
Year-over-year change: 71,000
Number of properties that are 90 or more days past due, but not in foreclosure: 574,000
Month-over-month change: 11,000
Year-over-year change: 92,000
Number of properties in foreclosure pre-sale inventory: 298,000
Month-over-month change: 2,000
Year-over-year change: 89,000
Number of properties that are 30 or more days past due or in foreclosure: 2,254,000
Month-over-month change: 84,000
Year-over-year change: 160,000
Add in ever-increasing insurance and property taxes, divorce, job relocation, and just life in general, and not being able to sell is bad for many people.
In other words, for many, it is life or death
I have been in RE for 25 years and have managed foreclosures since the 2008 crash. Unless things change, 2027 will not be pleasant for many.
September foreclosure activity is not out yet, but I bet it's pretty bad.
Posted on 10/22/26 at 9:11 am to TideCPA
I've often said if we could get off of our asses and put high speed rail up it would change the real estate market in a good way. Imagine living outside of New Orleans and being able to work in Houston. No need to pay either city's high prices. It lets people spread out without it being a hassle
Posted on 10/22/26 at 9:11 am to CatfishJohn
quote:
A huge portion of potential buyers have been removed from the market because they don't want to sell their current homes with their current rates.
Fair
Posted on 10/22/26 at 9:11 am to SlowFlowPro
Recently sold a rental house. Realtor told me what she thought we should ask.
I laughed and said 30k less than her.
Sold within a month. Nothing else in neighborhood has moved because they wont budge. I didnt care. I was tired of paying utilities, insurance and taxes on it and i still made 100k selling it.
I laughed and said 30k less than her.
Sold within a month. Nothing else in neighborhood has moved because they wont budge. I didnt care. I was tired of paying utilities, insurance and taxes on it and i still made 100k selling it.
Posted on 10/22/26 at 9:12 am to stout
quote:
No one is buying but sellers have not accepted that perhaps their house is worth less since interest rates are no longer in the 2s and 3s.
I don't know if it's an issue of "accepting" or if the alternative of holding onto your home becomes the "better" decision.
Posted on 10/22/26 at 9:12 am to stout
I tired to sell my rental last year. Pretty squarely starter home, but very nice on the inside and newly remodeled. Had dozens of people come through and had several comments that they really liked it, but with rates where they are at they were going to resign their lease and try again next year.
That, to me, is a huge issue for sellers. Rents are way less than the cost of ownership at the first time home buyer level, and that demographic has less flexibility
That, to me, is a huge issue for sellers. Rents are way less than the cost of ownership at the first time home buyer level, and that demographic has less flexibility
Posted on 10/22/26 at 9:13 am to CatfishJohn
quote:
I'd be in the market to buy a home, but I'm not because of rates of my current home.
If I was already at 6% or something, I'd buy a house yesterday.
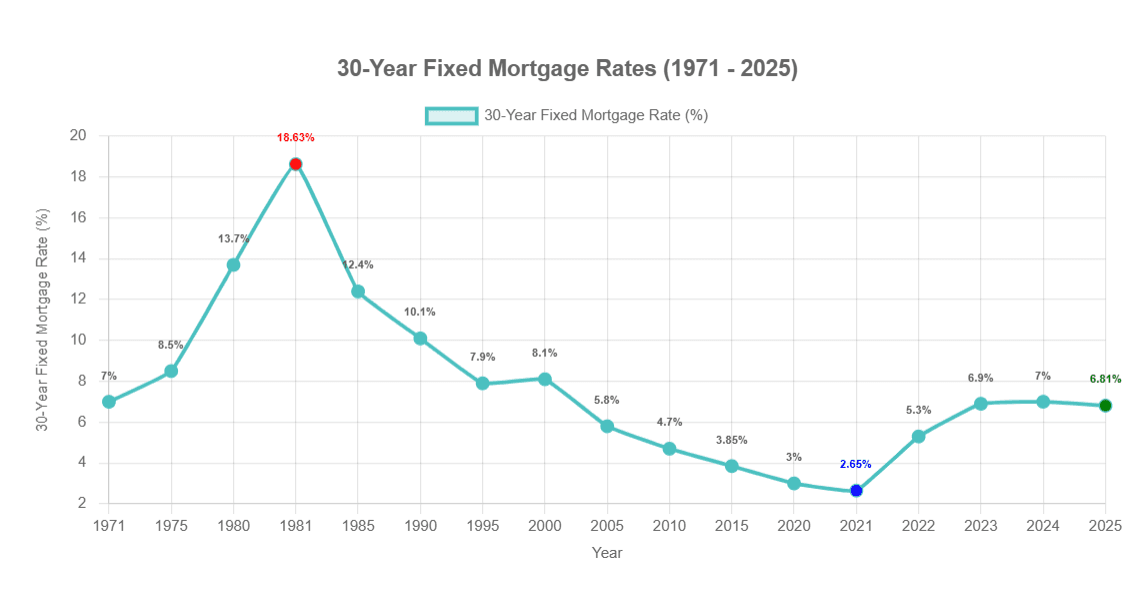
Rates aren't that bad, I'm sorry. The essentially free money days of 2-4% interest were an exception not the norm.
Economists were saying for years that the 3% interest rates were going to bite us in the arse at some point.
The hard truth is interest rates in the 5-8% range is healthy. That allows a healthy bond market and generally speaking helps with inflation.
Here's the hard truth: If you can't afford to "upgrade", then the reality is you were just allowed to upgrade too early in the past and you are current in the right house most likely. Hard pill to swallow for most but its the truth.
Posted on 10/22/26 at 9:14 am to baldona
quote:
Rates aren't that bad, I'm sorry. The essentially free money days of 2-4% interest were an exception not the norm.
You continue to be a total fricking idiot
Posted on 10/22/26 at 9:16 am to Mingo Was His NameO
I live next to a military base. So we have historically always had buyers, because military people liked buying a home, and then selling in 5 years for a little profit. I have had multiple neighbors do exactly that over the years.
I'm afraid that a lot of those military buyers are simply going to rent for their time here now.
I'm afraid that a lot of those military buyers are simply going to rent for their time here now.
Posted on 10/22/26 at 9:16 am to Mingo Was His NameO
quote:
You continue to be a total fricking idiot
Prove me wrong mingo, show me the historical graphs?
Also, show us your numbers on your rental? What did you buy it for and when, and what did you want to sell it for?
Just because you can't get as much as you want, doesn't mean you can't sell it
Here you go pal
This post was edited on 10/22/26 at 9:19 am
Posted on 10/22/26 at 9:19 am to baldona
quote:
Just because you can't get as much as you want, doesn't mean you can't sell it
This isn’t at all what I said, and your response to the other poster made zero sense in the context of what he posted.
You’re a fricking moron. Just thank the good lord above every single night your uncle set you up with mailbox money.
Literally not one person is arguing rates are not at historical averages but you are hung up on that for some reason
This post was edited on 10/22/26 at 9:20 am
 Page 2 of 4

Popular
Back to top
 Follow TigerDroppings for LSU Football News