




 0





- My Forums
- Tiger Rant
- LSU Recruiting
- SEC Rant
- Saints Talk
- Pelicans Talk
- More Sports Board
- Fantasy Sports
- Golf Board
- Soccer Board
- O-T Lounge
- Tech Board
- Home/Garden Board
- Outdoor Board
- Health/Fitness Board
- Movie/TV Board
- Book Board
- Music Board
- Political Talk
- Money Talk
- Fark Board
- Gaming Board
- Travel Board
- Food/Drink Board
- Ticket Exchange
- TD Help Board
Customize My Forums- View All Forums
- Show Left Links
- Topic Sort Options
- Trending Topics
- Recent Topics
- Active Topics
Started By
Message
Posted on 9/18/26 at 11:05 am to stout
Its 2008 but worse
Posted on 9/18/26 at 11:06 am to Azkiger
quote:
Does that sound like micro or macroeconomics to you?
Since real estate markets are hyper-local, pricing is fundamentally microeconomic
“Life happens” may force someone to sell at a bad time, but that doesn’t make it a macroeconomic issue. If the dollar keeps losing value, hard assets like real estate generally cost more dollars over time.
That's why everyone always says to buy assets. No one says to hold onto your cash. People who get this have a real chance over the next 2-3 years to substantially increase their net worth.
So if someone loses money on a house, that’s usually a local market and timing issue, not proof that dollar devaluation makes real estate worth less.
Posted on 9/18/26 at 11:07 am to stout
You really are clueless aren’t you? Lol very few people stay in the same house long enough to pay it off. They are concerned with the payment not the principle and dropping the purchase price by 20k on a 30 year mortgage in negligible. A current 30 year mortgage on a 300k house depending upon where you live is roughly $2100 per month. Reducing that same house to a 280k purchase price saves you about $50 per month; the very definition of negligible. What other basic economic facts do you need help in understanding?
Posted on 9/18/26 at 11:09 am to Rip Torner
What happens when the house you bought for 300k is now worth 280k, and you have only chipped away 15k off the principle since purchase?
And you need to buy another 280k house at 7%
And you need to buy another 280k house at 7%
Posted on 9/18/26 at 11:11 am to Friscodog
quote:
Understand your point, but why would I want to buy your "used" home for 300K when for only 50K more
quote:
Friscodog
And think how much you save by not needing toilets
Posted on 9/18/26 at 11:11 am to Hateradedrink
quote:
What happens when the house you bought for 300k is now worth 280k, and you have only chipped away 15k off the principle since purchase?
And you need to buy another 280k house at 7%
Rent the property and buy the new one
Posted on 9/18/26 at 11:13 am to SDVTiger
That’s not an option for everyone and quite possibly would end up losing money if rent goes down but you still owe.
I hope we don’t get to 2008 again where it’s cheaper for people to just walk away from their mortgage than pay it in any capacity.
I hope we don’t get to 2008 again where it’s cheaper for people to just walk away from their mortgage than pay it in any capacity.
Posted on 9/18/26 at 11:14 am to Rip Torner
quote:
They are concerned with the payment not the principle
Then those people, much like you, are economic simpletons
A lower purchase price now also means a better shot at equity building when the market rebounds. Even the 2008 crash only took about 6 years to recover nationally.
And guess what the average time a family stays in a home is?
It's 7 years
quote:
Reducing that same house to a 280k purchase price saves you about $50 per month
It's actually $133 per month so over the 7 years the average family stays, that saves about $11K cash
This post was edited on 9/18/26 at 11:23 am
Posted on 9/18/26 at 11:15 am to Hateradedrink
How isnt it an option for everyone?
Posted on 9/18/26 at 11:17 am to stout
quote:
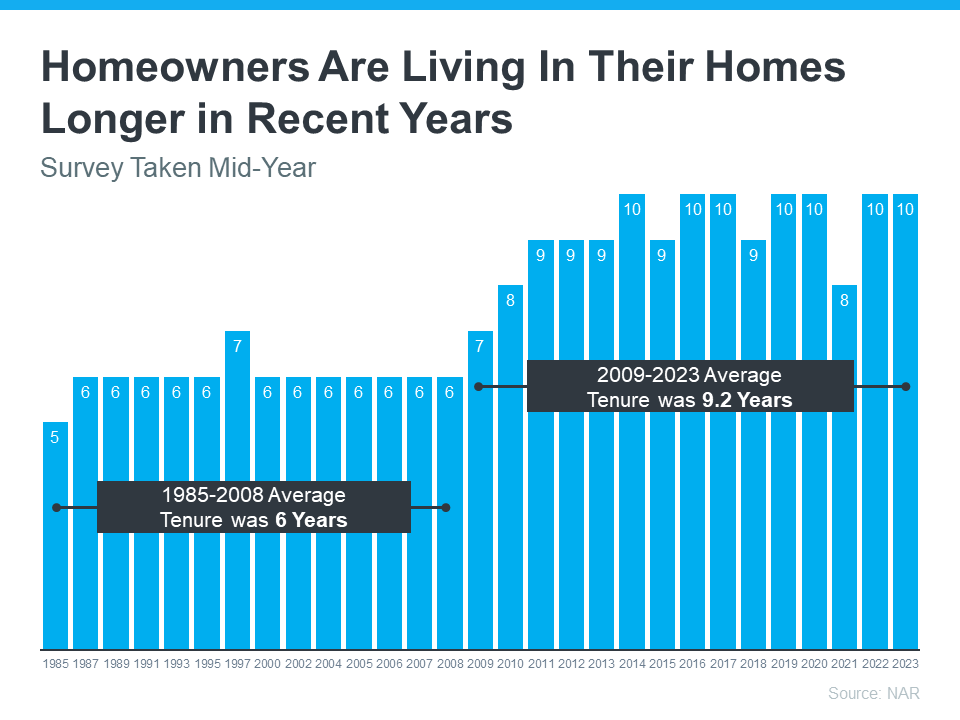
And guess what the average time a family stays in a home is?
It's 7 years
used to be, people have been staying in their homes longer now.
Posted on 9/18/26 at 11:19 am to SDVTiger
quote:
How isnt it an option for everyone?
Divorce is the most common
Job loss
People getting sick
Those 3 are the top leading foreclosure reasons, too in order
DTI is another one. It's going to be hard to get a new mortgage if you were already stretching to buy the first one.
Posted on 9/18/26 at 11:19 am to alabamabuckeye
quote:
We have a lot of economists and constitutional lawyers on this board, it’s pretty incredible
In fairness stout follows the residential home market more than anyone else here. If there is anyone I would trust on this slice of the economy to know anything useful here it would be him.
Posted on 9/18/26 at 11:21 am to Dire Wolf
quote:
people have been staying in their homes longer now.
Yeah, last I saw something nearly 50% of people are staying in their homes for 10 years on average now.
That only strengthens my argument that saving $20K on a purchase price in the scenario makes a difference. 10 years means $16K in cash saved on payments.
Posted on 9/18/26 at 11:25 am to stout
If they arent in those categories you listed then everyone has the chance to rent the curent home "under water" and buy a new one
If they are part of the group you listed then ppl should just rent not buy
If they are part of the group you listed then ppl should just rent not buy
Posted on 9/18/26 at 11:29 am to stout
quote:
That only strengthens my argument that saving $20K on a purchase price in the scenario makes a difference. 10 years means $16K in cash saved on payments.
It also means sellers have a little more wiggle room to drop the prices.
The people in the house under 5 or so years, are kind of shite out of luck because they’ve bought after housing inflation to varying degrees.
This year has been a game of chicken because sellers are more often than not are also buyers. So dropping too much removes them from the buyer category.
Posted on 9/18/26 at 11:30 am to stout
quote:
Sellers are absorbing recent economic data and shifting behavior in real time.
Buyers: your leverage went up again this week. Ignore sticker prices - anchor to current FMV.
Houston has been insulated for the past 3-4 yrs, but its beginning to hit here now. More houses on the market for longer periods of time.
Only going to get worse with over 7% rates right now. I think I saw Shady Acres, which is just outside the Heights has 9 months worth of inventory listed right now and its not moving.
Posted on 9/18/26 at 11:31 am to SDVTiger
quote:
then everyone has the chance to rent the curent home "under water" and buy a new one
Sure, but not everyone wants to, and that also creates a whole other list of issues.
Do you own any rentals?
Cash flow can be a problem. Especially if someone is cash poor from having to buy two homes. They will have to make sure they have enough cash to cover vacant periods, repairs, etc.
Also, on average, you lose about two months' rent just to cover insurance, taxes, and maintenance. At least I do on mine, so there are going to be at least two months out of the year that they will be paying two mortgages unless by some miracle, they are clearing enough off the monthly rent above their payments to cover that. Most don't make enough. It's the whole reason I will never pay full price for a rental if I am considering financing it. Margins are too small.
Again, that is in a perfect case scenario where they get good long-term renters, have zero vacancies, and minimal repair and maintenance costs.
Not everyone can cash flow that or wants to deal with it.
Posted on 9/18/26 at 11:32 am to Dire Wolf
quote:
This year has been a game of chicken because sellers are more often than not are also buyers. So dropping too much removes them from the buyer category.
Yep. A completely frozen market
Posted on 9/18/26 at 11:34 am to stout
quote:
Do you own any rentals?
Yes. I understand how it works
quote:
Not everyone can cash flow that or wants to deal with it.
Never said they did. Just said everyone has the option to buy anothet home and rent the current one versus having to short sale or take a loss
That seems like it would be a better strategy then sell when things calm down
 Page 2 of 4

Popular
Back to top
 Follow TigerDroppings for LSU Football News