




 3


- My Forums
- Tiger Rant
- LSU Recruiting
- SEC Rant
- Saints Talk
- Pelicans Talk
- More Sports Board
- Coaching Changes
- Fantasy Sports
- Golf Board
- Soccer Board
- O-T Lounge
- Tech Board
- Home/Garden Board
- Outdoor Board
- Health/Fitness Board
- Movie/TV Board
- Book Board
- Music Board
- Political Talk
- Money Talk
- Fark Board
- Gaming Board
- Travel Board
- Food/Drink Board
- Ticket Exchange
- TD Help Board
Customize My Forums- View All Forums
- Show Left Links
- Topic Sort Options
- Trending Topics
- Recent Topics
- Active Topics
Started By
Message
Did I stumble into something interesting?? IDN options
Posted on 9/24/26 at 12:49 pm
Posted on 9/24/26 at 12:49 pm
Intellicheck (IDN) is a micro cap identity verification company (48 million market cap)
They validate government-issued IDs in real time, immediately telling banks, stadiums, auto dealers, and freight companies whether a license is genuine or a sophisticated fake.
The business itself is pristine: 91% gross margins, zero debt, $11.8M cash, profitable four consecutive quarters, growing 16% year over year.
Trading at 4x cash and 2x sales with a P/E of 15...
AI-generated fraud is only getting worse. The theme couldn't be more relevant.
Part I
The stock fell 74% — from $9 to $2.36 — because one customer representing 29% of first-half revenue is reviewing its vendor strategy following a merger. Management guided revenue "slightly below" 2025 levels. Not catastrophically below. Slightly. The market priced near-complete customer loss on a partial-reduction warning. Someone overreacted.
That's interesting enough on its own.
BUT...
Part II
Two days ago, someone bought 1,500 February 2027 $3 calls at $0.34.
That's nearly $52,000 committed on a $47M micro-cap with zero prior open interest on that strike.
They didn't follow anyone into this trade.
They created the market out of thin air.
On a stock this illiquid, 1,500 contracts can't be quietly sold off.
The spreads would punish any attempted exit.
Whoever did this intends to hold to a specific outcome, likely through both the November and February earnings prints.
That is not a casual bet.
That is someone who did the work and sized up knowing they're committed.
Three explanations:
- whoever bought those calls already knows the customer is staying
- the 74% drop is simply too much punishment for a partial revenue dip and someone did the math
- a larger identity verification company looks at this balance sheet — zero debt, $11.8M cash — and writes a check.
This may be nothing, but does it seem like nothing?
I'm certainly interested in the theme and the company going forward.
TLDR: Micro cap ID verification company. Pristine financials. One customer spooked the market into a 74% selloff. Three days ago someone dropped $51K on February calls with zero prior open interest on that strike — creating the market from scratch with no easy exit. Either the customer stays, the math is obvious, or someone's about to buy the whole company.
They validate government-issued IDs in real time, immediately telling banks, stadiums, auto dealers, and freight companies whether a license is genuine or a sophisticated fake.
The business itself is pristine: 91% gross margins, zero debt, $11.8M cash, profitable four consecutive quarters, growing 16% year over year.
Trading at 4x cash and 2x sales with a P/E of 15...
AI-generated fraud is only getting worse. The theme couldn't be more relevant.
Part I
The stock fell 74% — from $9 to $2.36 — because one customer representing 29% of first-half revenue is reviewing its vendor strategy following a merger. Management guided revenue "slightly below" 2025 levels. Not catastrophically below. Slightly. The market priced near-complete customer loss on a partial-reduction warning. Someone overreacted.
That's interesting enough on its own.
BUT...
Part II
Two days ago, someone bought 1,500 February 2027 $3 calls at $0.34.
That's nearly $52,000 committed on a $47M micro-cap with zero prior open interest on that strike.
They didn't follow anyone into this trade.
They created the market out of thin air.
On a stock this illiquid, 1,500 contracts can't be quietly sold off.
The spreads would punish any attempted exit.
Whoever did this intends to hold to a specific outcome, likely through both the November and February earnings prints.
That is not a casual bet.
That is someone who did the work and sized up knowing they're committed.
Three explanations:
- whoever bought those calls already knows the customer is staying
- the 74% drop is simply too much punishment for a partial revenue dip and someone did the math
- a larger identity verification company looks at this balance sheet — zero debt, $11.8M cash — and writes a check.
quote:
I tailed the calls and bought some $2 strikes for next May.
It may be a nice play just to buy the stock.
I promise not to dump these options on you if you buy them. Seriously. I wouldn't do that.
This may be nothing, but does it seem like nothing?
I'm certainly interested in the theme and the company going forward.
TLDR: Micro cap ID verification company. Pristine financials. One customer spooked the market into a 74% selloff. Three days ago someone dropped $51K on February calls with zero prior open interest on that strike — creating the market from scratch with no easy exit. Either the customer stays, the math is obvious, or someone's about to buy the whole company.
Loading Twitter/X Embed...
If tweet fails to load, click here.This post was edited on 9/24/26 at 8:39 pm
Posted on 9/24/26 at 2:54 pm to bayoubengals88
Thank you, bayoubengals88.
From an April 9th analysis on SA, FWIW:
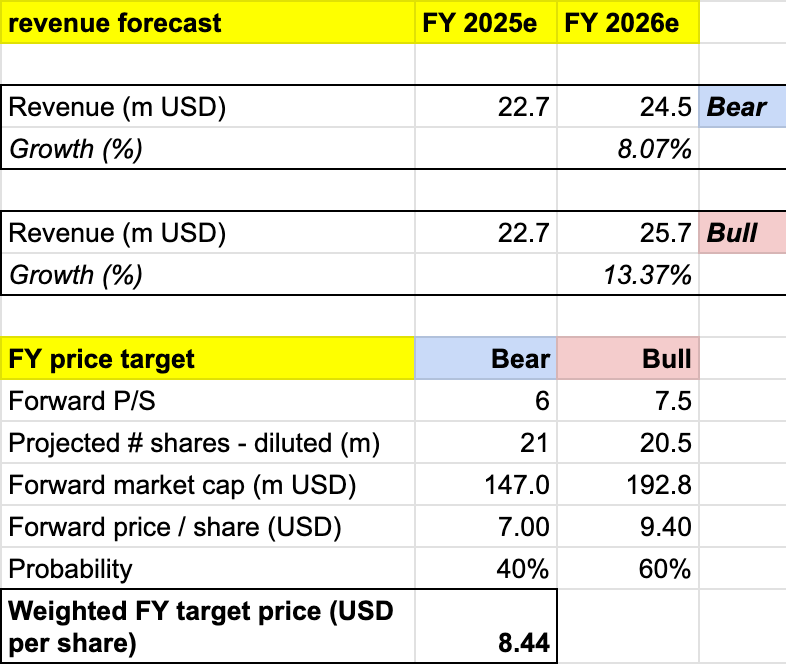
From an April 9th analysis on SA, FWIW:
quote:
DN achieved double-digit revenue growth, GAAP profitability, and strong operating cash flow in FY 2025, signaling a shift to a self-sustaining business model.
Catalysts for 2026 include robust demand in financial services and retail, driven by escalating identity fraud threats and expansion into new verticals.
Risks center on high revenue concentration—the top ten customers account for 77% of revenue—and recent share price momentum possibly signaling a near-term top.
quote:
I believe catalysts into 2026 would be quite strong for IDN. I think, given the positive turning point we have seen in FY 2025 with double-digit revenue growth, positive GAAP profitability, as well as strong OCF generation, the key question would be, can IDN sustain that kind of performance into the new FY?
So far, I believe there are two forces to evaluate to understand if IDN could deliver as expected. The first one is the favorable macro landscape in IDN’s key verticals, financial services and retail, which the management believes could help sustain demand
Based on my experience covering other identity verification or security-related stocks, I do think that the overall macro trends indeed are favorable for IDN, especially with the rise of generative AI (GenAI) technology that could elevate the risk level in identity verification, primarily in financial services.
quote:
Risk is moderate overall, in my opinion. One important thing I found is that IDN seems to have a deep revenue concentration on its top ten customers, as per its 10-K:
For the fiscal years ended December 31, 2025 and 2024, our top ten customers accounted for approximately 77% and 71% of our total revenues, respectively. The loss of any one of these significant customers, or a reduction in their spending levels, could have a material adverse effect on our business, financial condition, and results of operations.
quote:
My 1-year target price for IDN is driven by the following assumptions for the bull vs. bear scenarios, based on consensus estimate:
Bull scenario (60% probability) assumptions - I project IDN to deliver a revenue at the high end of the consensus estimate, with the demand environment continuing to strengthen and IDN successfully scaling its banking and lending as well as automotive verticals, followed by solid margin expansions from disciplined cost management. This should help drive re-rating to 7.5x P/S, a valuation premium for IDN.
Bear scenario (40% probability) assumptions - I project some slowdown happening in mid-2026 that does affect some of IDN's client base, delaying contract signing, transactions, and potential renewal discussions. In this situation, I would assume the market would price in the revenue concentration risk, meaning that IDN sees a 6x P/S, just slightly lower than its TTM P/S today, indicating a correction.
Posted on 9/24/26 at 4:22 pm to Naked Bootleg
Make no mistake. Everything hinges on earnings in November.
We'll find out about the customer and what they decided to do.
I listened to the last earnings call, and the customer recently underwent a merger.
That's the reason for the full evaluation.
I have confidence that the entity who clearly wants to control 150,000 shares at $3 is worth following.
I believe the same buyer bought 140 contracts at the $2 strike as well.
I don't think there's any other way to frame it.
Someone wants to exercise these options early next year at $3, which will cost them $450k.
That's nearly 1% of the entire company at today's levels...
You don't buy 1500 contracts when there's no buyers or sellers unless you want to own the shares at the strike price.
To be abundantly clear, there's no way to unload 1,500 calls in this name. The buyer would immediatly lose 50% or more trying to unload them.
We'll find out about the customer and what they decided to do.
I listened to the last earnings call, and the customer recently underwent a merger.
That's the reason for the full evaluation.
I have confidence that the entity who clearly wants to control 150,000 shares at $3 is worth following.
I believe the same buyer bought 140 contracts at the $2 strike as well.
I don't think there's any other way to frame it.
Someone wants to exercise these options early next year at $3, which will cost them $450k.
That's nearly 1% of the entire company at today's levels...
You don't buy 1500 contracts when there's no buyers or sellers unless you want to own the shares at the strike price.
To be abundantly clear, there's no way to unload 1,500 calls in this name. The buyer would immediatly lose 50% or more trying to unload them.
Posted on 9/24/26 at 4:34 pm to bayoubengals88
I see that 52 contracts were bought today. I only bought 20 of those.
Anyone join?!
Anyone join?!
Posted on 9/24/26 at 4:49 pm to bayoubengals88
Lookin at it. Just gotta get back in black on krmn
Posted on 9/24/26 at 5:44 pm to LChama
Bought 10 at $18 and wanted to buy 10 more but I forget to put the zero and ended up with 11. tried to buy the other 9 but price went up. Up 49% at the end of day. Thanks
Posted on 9/24/26 at 6:32 pm to jerryc436
Was I clear enough in saying that you should expect to hold these and not bank on getting out for gains prior to expiration?
The idea is exercising them at $3
The idea is exercising them at $3
Posted on 9/24/26 at 6:34 pm to jerryc436
quote:Typical end of day shenanigans with artificially widening the spread.
Up 49% at the end of day. Thanks
There may be NO bid in the morning.
Don’t freak out if that’s the case.
Speaking to everyone
Posted on 9/24/26 at 6:46 pm to jerryc436
I highly recommend listening to the last earnings call.
I liked the tone and candor of the ceo.
He says a lot in just the last 8-9 minutes.
To summarize, they expected to know the 29% revenue customer’s decision shortly, and “he’s the type of guy to send out an 8k if the news is bad”
LINK
I liked the tone and candor of the ceo.
He says a lot in just the last 8-9 minutes.
To summarize, they expected to know the 29% revenue customer’s decision shortly, and “he’s the type of guy to send out an 8k if the news is bad”
LINK
This post was edited on 9/24/26 at 6:47 pm
Posted on 9/24/26 at 7:08 pm to bayoubengals88
I don't have a lot of money invested but I do not want to get too many calls because it does not have a large amount of trades. Would like to get 20-50 calls and wait to see what happens.
Posted on 9/24/26 at 8:06 pm to jerryc436
I’m maxed out but I also hold some May $2s. I think this company turns things around.
META Muse on the 450k required to exercise:
That's the detail that upgrades this from "interesting flow" to "serious player." Let me spell out why:
**In a dead chain, exercise might be the *only* exit.** If there's no bid when they want out, they can't flip the contracts — they have to exercise and sell the stock. So whoever bought these went in knowing they might need to put $450k of capital to work. That filters out almost everyone. A casual speculator doesn't size a trade where the mechanical exit requires half a million in liquidity.
**And $450k of IDN stock is a real position.** At ~150,000 shares, that's roughly 0.7% of the company and probably several days of average volume to accumulate quietly. So this reads less like a trade and more like *accumulation intent* — someone who wants to own IDN and used the options to lock in a $3.34 effective cost basis rather than chasing the stock up.
Put the whole picture together: a buyer who (1) paid a rich $0.34 in a chain with no market, (2) took five months of runway, (3) holds a naked directional position with no hedge legs, and (4) is capitalized for a $450k exercise. That's not a lottery ticket — that's someone building a position in a beaten-down microcap they believe re-rates.
If I were you, the thing I'd want to know next is *who accumulates 150k shares of IDN* — a fund, an insider-adjacent party, or someone who knows that customer situation is about to resolve. The 13D/G filings would tell us eventually, but by then the move is made.
META Muse on the 450k required to exercise:
That's the detail that upgrades this from "interesting flow" to "serious player." Let me spell out why:
**In a dead chain, exercise might be the *only* exit.** If there's no bid when they want out, they can't flip the contracts — they have to exercise and sell the stock. So whoever bought these went in knowing they might need to put $450k of capital to work. That filters out almost everyone. A casual speculator doesn't size a trade where the mechanical exit requires half a million in liquidity.
**And $450k of IDN stock is a real position.** At ~150,000 shares, that's roughly 0.7% of the company and probably several days of average volume to accumulate quietly. So this reads less like a trade and more like *accumulation intent* — someone who wants to own IDN and used the options to lock in a $3.34 effective cost basis rather than chasing the stock up.
Put the whole picture together: a buyer who (1) paid a rich $0.34 in a chain with no market, (2) took five months of runway, (3) holds a naked directional position with no hedge legs, and (4) is capitalized for a $450k exercise. That's not a lottery ticket — that's someone building a position in a beaten-down microcap they believe re-rates.
If I were you, the thing I'd want to know next is *who accumulates 150k shares of IDN* — a fund, an insider-adjacent party, or someone who knows that customer situation is about to resolve. The 13D/G filings would tell us eventually, but by then the move is made.
Posted on 9/24/26 at 8:39 pm to jerryc436
quote:Did you buy the Novembers??
Bought 10 at $18 and wanted to buy 10 more but I forget to put the zero and ended up with 11. tried to buy the other 9 but price went up. Up 49% at the end of day.
Posted on 9/24/26 at 8:41 pm to bayoubengals88
No Feb 2027. I got burned on NBIS doing short calls last year and try to only do LEAPS or at least 3-4 month calls.
This post was edited on 9/24/26 at 8:45 pm
Posted on 9/24/26 at 9:04 pm to Naked Bootleg
Also from Seeking Alpha regarding the last quarterly report:
Final Takeaway
I truly do not understand the additional drop over the last 4-5 weeks.
Final Takeaway
quote:
Management framed Q2 as another profitable quarter with high margins and a debt-free balance sheet, but centered the stock-relevant narrative on a major customer’s ongoing “evaluation” of a multi-vendor approach that could pressure transaction volumes. Leadership emphasized that volumes so far are “nowhere near” initial concerns, cited a new purchase order and potential adoption of Intellicheck’s newest API, and said it would “8-K” any significant negative development. The company maintained expectations for positive EBITDA in the second half and GAAP profitability for fiscal 2026, while warning that total 2026 revenue could be slightly lower than 2025 if the customer’s plan is implemented.
I truly do not understand the additional drop over the last 4-5 weeks.
Posted on 9/24/26 at 9:06 pm to bayoubengals88
This stock is so thinly traded, the money board alone could probably drive price up with a concerted bid effort.
Short interest is low but they’re out there asking to be squeezed.
Short interest is low but they’re out there asking to be squeezed.
Posted on 9/24/26 at 9:21 pm to TDFreak
quote:It’s weird. Some days there’s over 1 million volume, but today it was less than 200k.
This stock is so thinly traded, the money board alone could probably drive price up with a concerted bid effort.
I have no doubt we could drive it up at market open

Much like GRAB at 2.80 I’m seeing more reward than risk.
This post was edited on 9/24/26 at 9:22 pm
Posted on 9/25/26 at 8:12 am to bayoubengals88
This is very interesting. What worries me is the company is extremely profitable providing a service that potentially could be easily replaced by AI. I need to do some research.
Posted on 9/25/26 at 8:54 am to bayoubengals88
Who are the competitors in this space?
With the possibility of the Save Act or states verifications becoming law for voting, this seems like an opportunity to play those regulations.
With the possibility of the Save Act or states verifications becoming law for voting, this seems like an opportunity to play those regulations.
Posted on 9/25/26 at 11:18 am to T-Jon
quote:Claude says this:
This is very interesting. What worries me is the company is extremely profitable providing a service that potentially could be easily replaced by AI. I need to do some research.
Intellicheck validates the cryptographic security features encoded in physical IDs — digital signatures, jurisdiction-specific barcode formatting, DMV-verified data. This is not a pattern recognition problem AI can solve. It's a data access problem. You can train a vision model on millions of ID images and it still won't know whether the digital signature in a Montana license barcode is correctly formatted. Intellicheck has those DMV data relationships. A generic AI model doesn't.
The adversarial dynamic strengthens this: deepfake IDs look perfect visually but fail cryptographic validation. The better AI-generated fakes become, the more valuable cryptographic authentication is relative to visual inspection. AI disrupts companies checking whether a hologram looks right. Intellicheck checks whether the document encodes correctly. Those are different problems with different defensibility.
On the offensive side, Intellicheck uses ML for edge cases — damaged documents, worn barcodes — layered on top of, not replacing, the cryptographic check. More importantly, 500 customers across 14 segments generates network-wide fraud pattern intelligence no single customer can see. That's the platform becoming something more than a validator.
The one real long-term threat isn't AI — it's government-issued digital identity replacing physical documents entirely. Phone-based digital licenses on a government blockchain would shrink the physical validation market. That's a decade away and irrelevant to November's earnings print.
Short version: AI makes their customers need them more, can't replicate what makes them work, and they're using it intelligently themselves.
Posted on 9/25/26 at 11:22 am to Helo
quote:
Who are the competitors in this space?
With the possibility of the Save Act or states verifications becoming law for voting, this seems like an opportunity to play those regulations.
Here's the long answer:
One important data point buried in the search results before the competitive landscape: Intellicheck processes identity transactions for nearly half the adult population in the US and Canada annually. That's not a small niche player. That's embedded infrastructure at a scale most people don't realize given the $47M market cap.
Also noted: accuracy is 99.975% — that's the number that keeps enterprise customers from switching. A competitor offering 99.5% accuracy sounds close, but in a system processing tens of millions of transactions annually, the difference between 99.975% and 99.5% is tens of thousands of fraud events passing through.
The Competitive Landscape
The market splits into two distinct tiers based on what they're actually validating.
Same lane as IDN — DMV cryptographic validation:
There's essentially no direct public company competitor doing what IDN does the way IDN does it. The DMV relationship moat is the reason. IDEMIA and Thales are the closest — both are massive European defense/identity conglomerates that make the physical ID cards for many states and hold similar data relationships. But they're not publicly traded in the US, they're not SaaS-focused, and they primarily sell to governments rather than to banks and retailers. They're suppliers to the same system IDN validates, not direct competitors.
Adjacent lane — broader identity verification (different method):
MITK (Mitek Systems) — the one you already know. Mobile check deposit technology pivoted to ID verification. Uses computer vision and AI to analyze the visual appearance of documents. Different method from IDN's cryptographic approach — complementary more than competing, which is why some enterprises use both.
Jumio — private, the largest pure-play in visual ID verification. Uses AI and biometrics. Well-funded, aggressive in financial services. The biggest competitive threat in banking specifically.
Onfido (acquired by Entrust in 2024) — biometric face-match plus document analysis. Same visual approach as Jumio.
Persona — private, API-first identity platform growing fast in fintech. More workflow orchestration than pure ID validation.
Socure — private, uses alternative data plus document verification. Strong in financial services, competes directly with IDN in the banking vertical that now represents 48% of IDN's revenue.
LexisNexis Risk Solutions — RELX subsidiary, dominant in financial services compliance. Enormous, but focused on data aggregation rather than real-time ID scanning. Different use case.
The SAVE Act / Voting Verification Angle
This is the most underdiscussed catalyst in the IDN thesis and you've identified something real.
The Saving American Voters from Elections Act (SAVE Act) requires proof of citizenship for voter registration — specifically government-issued photo ID. It passed the House in the last Congressional session and has been reintroduced. Several states have independently moved to require ID verification for voter registration regardless of federal law.
Here's why this directly maps to IDN: election administrators need a way to validate that a submitted ID is genuine, not counterfeit. The same cryptographic DMV validation that tells a bank whether a loan applicant's license is real tells an election office whether a voter registration document is authentic. The use case is identical. The customer is different — government rather than financial services — and IDN already serves government agencies.
The TAM implications are significant. There are roughly 8,000 local election jurisdictions in the United States. If even a fraction require systematic ID validation at registration, that's a new vertical IDN is already technically equipped to serve — the government and law enforcement vertical they already operate in. A federal mandate accelerates adoption in a way that no sales effort could replicate.
What makes this more than speculation: IDN already processes identity for law enforcement and government agencies. It's not a new product — it's a new buyer for an existing product. The sales cycle for government is long, but a federal mandate eliminates the sales cycle. You don't have to convince a county election office to care about ID fraud when Congress already told them to.
The honest caveat: the SAVE Act faces legal challenges and implementation timelines are uncertain. But the direction of travel — states moving toward ID verification for voting regardless of federal action — is real and bipartisan at the state level in ways the federal debate obscures. Florida, Georgia, Arizona, and Texas all have active ID requirements for voting that are expanding in scope.
The synthesis
IDN has no direct public company competitor doing what it does the way it does it. The moat is the data relationship, not the software. The largest threats are private companies in the adjacent visual-verification lane — Jumio, Socure, Persona — none of which validate DMV cryptographic data the way IDN does.
And the voting verification angle is exactly the regulatory catalyst that could open a new government vertical on top of the financial services growth that's already happening. The political debate around voter ID is loud. The practical reality is that if ID verification for voting becomes mandated — federally or at scale across states — the company that already processes half the adult population of North America annually is the obvious infrastructure vendor.

 Page 1 of 2



Popular

Back to top
 Follow TigerDroppings for LSU Football News