




 2




- My Forums
- Tiger Rant
- LSU Recruiting
- SEC Rant
- Saints Talk
- Pelicans Talk
- More Sports Board
- Coaching Changes
- Fantasy Sports
- Golf Board
- Soccer Board
- O-T Lounge
- Tech Board
- Home/Garden Board
- Outdoor Board
- Health/Fitness Board
- Movie/TV Board
- Book Board
- Music Board
- Political Talk
- Money Talk
- Fark Board
- Gaming Board
- Travel Board
- Food/Drink Board
- Ticket Exchange
- TD Help Board
Customize My Forums- View All Forums
- Show Left Links
- Topic Sort Options
- Trending Topics
- Recent Topics
- Active Topics
Started By
Message
Does anyone here do the Jason Kelly investment strategy?
Posted on 9/28/26 at 7:13 am
Posted on 9/28/26 at 7:13 am
Looking for the pros and cons of his system.
Posted on 9/28/26 at 7:18 am to LSUFAN82
nm
This post was edited on 9/28/26 at 9:15 pm
Posted on 9/28/26 at 9:21 am to LSUFAN82
EDIT: The guy above is talking about something else -- not Jason Kelly. If you have any specific questions, let 'em rip.
Yes, for over a decade.
I retired at 52. People around me are just starting to realize that, no really, I'm retired. They're also starting to ask "how is he buying that?"
Pros: Lots of money.
Cons: Lots of volatility when growing. Less volatility, but still volatility when taking income.
I've been through major dips. It gives you the sads. No way to get away from that emotion.
I've been through the recoveries. It gives you the happys. Glad to have that emotion.
I don't think Jason will mind me posting this which kind of gets to the point at least on his most aggressive plan, 9Sig. He wrote it on 9/6/2026.
Yes, for over a decade.
I retired at 52. People around me are just starting to realize that, no really, I'm retired. They're also starting to ask "how is he buying that?"
Pros: Lots of money.
Cons: Lots of volatility when growing. Less volatility, but still volatility when taking income.
I've been through major dips. It gives you the sads. No way to get away from that emotion.
I've been through the recoveries. It gives you the happys. Glad to have that emotion.
I don't think Jason will mind me posting this which kind of gets to the point at least on his most aggressive plan, 9Sig. He wrote it on 9/6/2026.
quote:
9Sig: The Risk We Chose
I wrote last Sunday about hybrid asset allocation as a potential way to reduce 9Sig’s drawdown in an extended bear market.
This prompted a renewed wave of research into the plan by subscribers and others, who hit upon what they thought was a gotcha: 9Sig would have been devastated by the dot-com crash. The deep, extended descent of the Nasdaq 100 (NDX) would have ground TQQQ down so severely that 9Sig’s recovery would have taken many years.
News to newcomers: this was a known risk at 9Sig’s inception.
We studied 9Sig’s vulnerability to a dot-com-like collapse before launch and flagged it in the January 2017 announcement as a cost of pursuing extraordinary returns.
I made a calculated choice to run a plan built for the much more common market environment featuring sharp setbacks and recoveries, not two-and-a-half-year collapses of more than 80% in the underlying index, caused by a euphoric bubble in zero-profit companies measuring performance in clicks and eyeballs.
This was not the same as claiming that no such event could ever happen again. It was a decision to stop fighting the last war and run a high-performance plan designed for the prevailing climate, not freak storms.
It has worked: 9Sig has compounded at 38.5% a year for more than 9½ years. The criticism, however, has merely changed form. First, the plan would never work. Then, its gains were luck. Now, the answer to every added year of live results is “so far” as the plan’s critics await a collapse. The standard keeps moving as the record grows.
With 9Sig nearing its tenth anniversary, this is a good time to revisit whether its known weakness can be reduced without dulling the engine that produced its returns.
Nothing in the current 9Sig plan is changing. This is a ten-year stress test, not a warning that I see a crash coming.
The HAA strategy I covered last Sunday and other systematic plans don’t come close to matching 9Sig’s compound annual growth rate. To investors who want to reduce drawdown and increase smoothness, 9Sig’s dot-com vulnerability can outweigh its extraordinary return. For many critics, the working assumption is that 9Sig will eventually meet disaster.
This may not be the case. We may go the rest of our lives without another dot-com collapse, as seemed most probable when we made our calculated choice nearly a decade ago. We’ve already gone a third of an investor’s lifetime with the top-performing approach this side of an overfit backtest. Maybe we’ll go another two decades of surprising everyone who keeps saying our performance is not sustainable.
So, the objection that 9Sig would have been devastated by dot-com doesn’t uncover a new risk; it identifies the bargain we made. We knew that, flagged such a collapse as an outlier, and made a plan that has excelled in the much more common market pattern.
But the black swan still swims and every finger-wagger can always say “so far” and “just you wait.” What if we could account for more of that risk without giving up what has worked?
I’ve got news for the permacritics: every added defense lowers exposure to profit potential. Every mainstream investment manager is taught to diversify as a way to reduce risk, then dutifully does so across every asset class—and almost always loses to SPY in the end.
Many highly ranked rules-based plans focus on maximum drawdown, Sharpe ratio, smoothness, and such. Those are useful measurements, particularly for risk-averse investors, but don’t define superiority. A strategy with substantially lower return usually looks better by those measures because it carries less equity or leverage exposure.
Back at the bench, my goal is not to make 9Sig crashproof, but to see if I can retain its essential return engine while preparing for tail risk.
The danger in this work is that as protection against an extremely rare event ramps up, overall performance ramps down. You know how to guarantee you won’t suffer in another dot-com crash? Stay out of the stock market.
This post was edited on 9/28/26 at 10:03 am
Posted on 9/28/26 at 1:54 pm to dstone12
Lead into gold.
Posted on 9/28/26 at 3:27 pm to dstone12
quote:
dstone12
You posted the Kelly Criterion, which is theoretically how much you should risk on each trade/position or gambling bet. In reality, it is far too aggressive and reckless when trading because KC doesn't consider the distribution of losses (only the average loss) and the possibility of multiple consecutive losing trades. Too many of my backtests show it blowing up an account with half Kelly due to a single bad trade from the tail end of the distribution or with quarter Kelly after a string of bad trades.
Posted on 9/28/26 at 3:28 pm to Omada
I simply posted what ai said the definition of the strategy is since we really didn’t get an explanation in the OP.
Posted on 9/28/26 at 3:44 pm to dstone12
Indeed. My thing is that anytime I see something I consider flawed (if not outright garbage) like Kelly Criterion or Sharpe ratio, I point out its problems because initial information on the internet often just mentions the benefits and what it should do in theory.
I like to think it's the financial equivalent of warning a friend to avoid the hot chick with BPD.
I like to think it's the financial equivalent of warning a friend to avoid the hot chick with BPD.
Posted on 9/28/26 at 8:10 pm to RoyalWe
Bragging about your high beta approach having high returns in a bull market and that tail risks haven't materialized yet is certainly a choice on his end. I wouldn't trust him, especially after this part:
quote:
Many highly ranked rules-based plans focus on maximum drawdown, Sharpe ratio, smoothness, and such. Those are useful measurements, particularly for risk-averse investors, but don’t define superiority. A strategy with substantially lower return usually looks better by those measures because it carries less equity or leverage exposure.
Posted on 9/28/26 at 8:40 pm to Omada
He has several versions of his growth plans. 9Sig is the most aggressive and not for everyone.
Posted on 9/28/26 at 8:53 pm to dstone12
And I’m telling you you’re posting something that has nothing to do with Jason Kelly.
Posted on 9/28/26 at 8:56 pm to Omada
Covid was a pretty big tail risk. I lost 7 figures in a week.
Posted on 9/28/26 at 9:12 pm to RoyalWe
Just to state again, the Kelly Criterion has nothing to do with Jason Kelly.
Posted on 9/28/26 at 9:14 pm to RoyalWe
will erase.
Posted on 9/28/26 at 9:18 pm to RoyalWe
quote:Do you not believe a global pandemic represents tail risk?
Covid was a pretty big tail risk. I lost 7 figures in a week.
Posted on 9/28/26 at 9:21 pm to RoyalWe
I’ve read several of your posts on here and am curious if you’ve looked at other strategies using tqqq? I just discovered it about a year ago and started running tqqq on about 1/3 of my portfolio. I’m in when qqq is above the 100 day sma and sell into sgov when its below. I did some reading and got AI to backtest this strategy vs 9sig and it shows similar returns with less drawdown risk. Just curious your thoughts on that.
Also I was wondering when you were aggressively growing what percent of your portfolio were you doing 9sig? I’m nervous to go much higher than 1/3, but I’m 47 and also feel a little behind. But it feels a little desperate to chase the higher returns with too high a percentage.
Just as an experiment I’ve also starting running 9 sig with a small amount of money in my HSA. So we’ll see how that goes. I do like the simplicity of the quarterly rebalance and not having to watch the market every day.
Also I was wondering when you were aggressively growing what percent of your portfolio were you doing 9sig? I’m nervous to go much higher than 1/3, but I’m 47 and also feel a little behind. But it feels a little desperate to chase the higher returns with too high a percentage.
Just as an experiment I’ve also starting running 9 sig with a small amount of money in my HSA. So we’ll see how that goes. I do like the simplicity of the quarterly rebalance and not having to watch the market every day.
Posted on 9/28/26 at 9:43 pm to 7flat
For those who want to know something high-level about the growth plans:
- It uses value cost averaging.
- You trade at the end of each quarter.
- Math determines the trades, so there's no debate on what to do.
- The version of plan you choose determines the stock ETF involved (and risk level)
I've read about several other TQQQ strategies, including moving in and out based on moving averages, but I haven't studied them enough to have a strong opinion. I was already familiar with 3Sig and 6Sig, so when Jason introduced 9Sig I was comfortable giving it a try.
I started with roughly 1/3 of my portfolio in 9Sig. I didn't intentionally keep increasing that allocation -- it simply outperformed everything else I owned and eventually became the dominant part of my portfolio. There was a lot of discussion over the years about rebalancing among the growth plans, but Jason's philosophy was basically to let the plans earn their place.
I would be cautious about increasing your allocation just because you feel behind. That's different from starting with an amount you're comfortable with and allowing it to grow over time. A large TQQQ position can feel very different during a major drawdown than it does in a backtest.
Eventually I reached the point where I had more than enough to retire, so my objective changed and I moved from 9Sig to Income Sig.
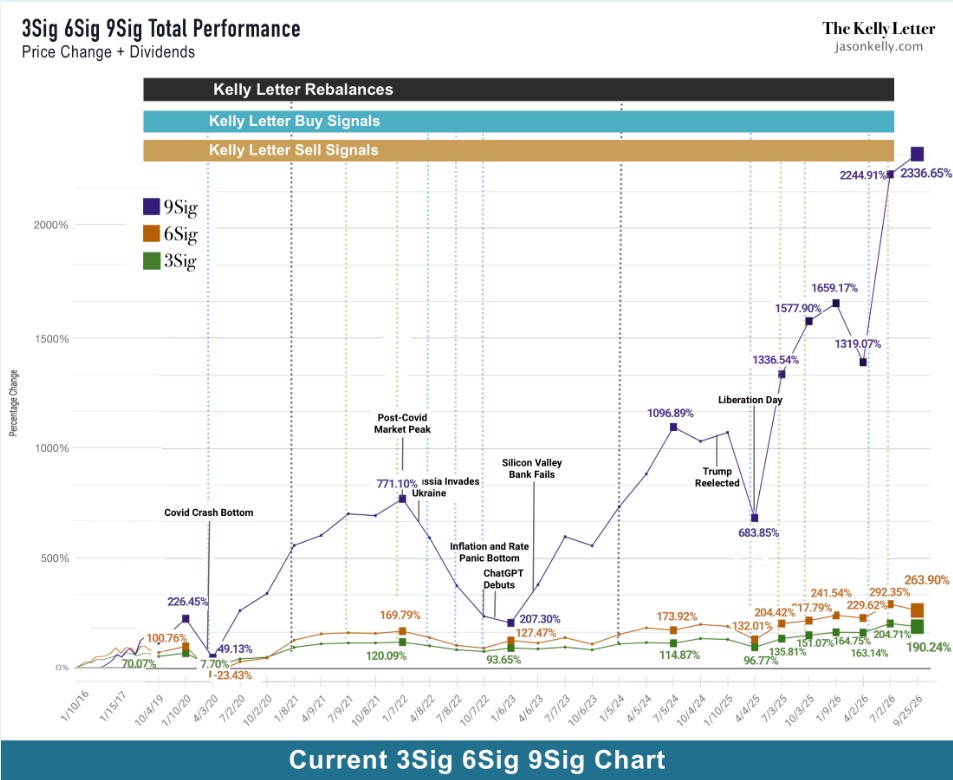
I'll post Jason's historical performance chart below for some perspective.
Your 100-day SMA strategy is interesting. "Similar returns with less drawdown" certainly gets my attention, although I'd want to look closely at the backtest assumptions and how 9Sig was modeled.
I also like your idea of running 9Sig with a smaller amount in the HSA. One of the things I've always liked about it is the simplicity of quarterly actions and not having to watch the market every day.
The Kelly Letter
- It uses value cost averaging.
- You trade at the end of each quarter.
- Math determines the trades, so there's no debate on what to do.
- The version of plan you choose determines the stock ETF involved (and risk level)
I've read about several other TQQQ strategies, including moving in and out based on moving averages, but I haven't studied them enough to have a strong opinion. I was already familiar with 3Sig and 6Sig, so when Jason introduced 9Sig I was comfortable giving it a try.
I started with roughly 1/3 of my portfolio in 9Sig. I didn't intentionally keep increasing that allocation -- it simply outperformed everything else I owned and eventually became the dominant part of my portfolio. There was a lot of discussion over the years about rebalancing among the growth plans, but Jason's philosophy was basically to let the plans earn their place.
I would be cautious about increasing your allocation just because you feel behind. That's different from starting with an amount you're comfortable with and allowing it to grow over time. A large TQQQ position can feel very different during a major drawdown than it does in a backtest.
Eventually I reached the point where I had more than enough to retire, so my objective changed and I moved from 9Sig to Income Sig.
I'll post Jason's historical performance chart below for some perspective.
Your 100-day SMA strategy is interesting. "Similar returns with less drawdown" certainly gets my attention, although I'd want to look closely at the backtest assumptions and how 9Sig was modeled.
I also like your idea of running 9Sig with a smaller amount in the HSA. One of the things I've always liked about it is the simplicity of quarterly actions and not having to watch the market every day.
The Kelly Letter
Posted on 9/29/26 at 8:08 am to RoyalWe
How does all the rebalancing compare to just letting it sit in TQQQ over the same period? When did you start? TQQQ has done really well since 2020 annualized. I get that the quarterly rebalance helps shelter losses but if this was a long hold for you it have performed even better if you let it ride.
Posted on 9/29/26 at 8:11 am to RoyalWe
Thanks, that’s helpful. Makes me feel better about my 1/3 allocation. Also good food for thought on rebalancing or not. I’ve kind of planned in my head to periodically rebalance but I see what you’re saying about sticking with the plan.
Posted on 9/29/26 at 9:25 am to BringBackTheToonces
quote:Others have done that analysis before and I've seen it, but whether it performed better or not it didn't convince me to alter my approach. I'm sure you could pop TQQQ into one of the many online tools and get exactly that information pretty quickly. In retirement, I've just become less concerned with tracking things. I started 9Sig at the beginning of 2017 when the Kelly Letter started. I had been a subscriber for years prior and so when he introduced the plan I started.
How does all the rebalancing compare to just letting it sit in TQQQ over the same period? When did you start?
quote:The largest factor that most people miss or don't discuss is the psychological impact of using a highly leveraged ETF. The highs are very high and the lows are very low. In my opinion, the Value Cost Averaging approach assists your emotions tremendously and therefore allows you to stick to the plan without panicking. When TQQQ is down you know that you have "dry powder" to buy the dip. When TQQQ is up you know that you're "buying dry powder" for the future. If you can't stick to a plan, then what's the point? If I just had TQQQ I think I would feel pretty helpless when it's down and I couldn't buy cheap.
I get that the quarterly rebalance helps shelter losses but if this was a long hold for you it have performed even better if you let it ride.
Posted on 9/29/26 at 12:38 pm to RoyalWe
just found his whole system on google docs.
i may allocate a small amount and try this 9sig system for shits and giggles.
i already have a ton of $$$ in VOO and QQQ.
i would use SGOV after liquidating those profits above certain amount each quarter.
i may allocate a small amount and try this 9sig system for shits and giggles.
i already have a ton of $$$ in VOO and QQQ.
i would use SGOV after liquidating those profits above certain amount each quarter.

 Page 1 of 2


Popular

Back to top
 Follow TigerDroppings for LSU Football News