




 6





- My Forums
- Tiger Rant
- LSU Recruiting
- SEC Rant
- Saints Talk
- Pelicans Talk
- More Sports Board
- Fantasy Sports
- Golf Board
- Soccer Board
- O-T Lounge
- Tech Board
- Home/Garden Board
- Outdoor Board
- Health/Fitness Board
- Movie/TV Board
- Book Board
- Music Board
- Political Talk
- Money Talk
- Fark Board
- Gaming Board
- Travel Board
- Food/Drink Board
- Ticket Exchange
- TD Help Board
Customize My Forums- View All Forums
- Show Left Links
- Topic Sort Options
- Trending Topics
- Recent Topics
- Active Topics
Started By
Message
KRMN-picks and shovels space position
Posted on 6/3/26 at 10:32 am
Posted on 6/3/26 at 10:32 am
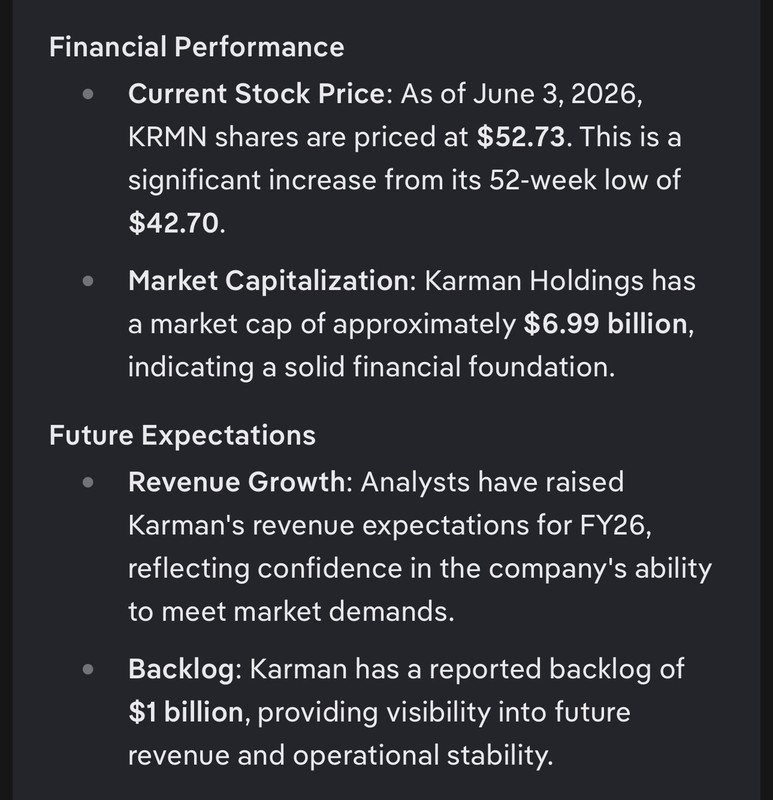
Business with Brian recommended this and CACi as opposed to rklb and asts which are not making money but losing.
This post was edited on 6/3/26 at 10:55 am
Posted on 6/3/26 at 11:03 am to LChama
It’s so scary to invest in anything new while trump is crashing the stock market
I might just wait until the adults are back in charge
I might just wait until the adults are back in charge
Posted on 6/3/26 at 11:28 am to el Gaucho
quote:
I might just wait
We will wave to you from the TD yacht
Posted on 6/3/26 at 11:49 am to LSUcam7
They coming to repo the yacht today
Posted on 6/3/26 at 11:55 am to LSUcam7
quote:
We will wave to you from the TD yacht
Aoc and bernie are gonna share the wealth
Posted on 6/3/26 at 7:00 pm to LChama
This post was edited on 6/3/26 at 7:06 pm
Posted on 6/3/26 at 7:27 pm to LChama
Following…
Posted on 6/3/26 at 8:58 pm to bayoubengals88
quote:
Following…
Let me know if you find the reasoning compelling. Im in for 200. Sold my other space stocks to get in here. Not sure if people are familiar with Business with Bob but thats who i first heard about it from.
May buy 5-10 Shares of CACi that he mentions as his no.1.
This post was edited on 6/3/26 at 9:12 pm
Posted on 6/4/26 at 4:19 pm to LChama
My first question was Space or Defense?
By revenue segment, as of Q1 2026, the breakdown is: Tactical Missiles and Integrated Defense Systems 30%, Space and Launch 29%, Hypersonics and Strategic Missile Defense 24%, and Maritime Defense Systems 17%.
So defense — combining tactical missiles, hypersonics, and maritime — accounts for roughly 71% of revenue, and space is 29%. This is primarily a defense company.
- But the specific nature of its defense work is what matters: it's not in legacy platforms like aircraft or armored vehicles.
- It's in the fastest-growing segments of DoD spending: hypersonic weapons, missile defense interceptors, guided munitions, and UAS systems.
- These programs have strong bipartisan support and are explicitly protected in budget discussions.
----------
There was a secondary offering at $61/share in late May for original private equity owners to sell shares. I'm talking about Trive Capital, who brought the company public in 2025. KRMN was not able to receive any money from the sale and no new shares were issued. Good. This sale was Trive making a distribution to their investors.
The good news is that Trive is now largely out of the way with their current ownership at only 3% after selling 65% of their shares in that recent round.
So $54/share isn't bad IMO, especially given the price targets, guidance, and backlog.


I bought 115 shares because, in short, EPS is expected to improve tremendously due to a good cleaning up of the capital structure:
The first and biggest is intangible amortization. Every time Karman acquires a company, accounting rules require it to assign fair values to the acquired customer relationships, technology, backlog, and brand — and then amortize those values over their estimated useful lives, typically 7–15 years. Amortization rose to $10.9 million in Q1 2026 alone, with intangible assets now sitting at $400.5 million net on the balance sheet. Annualized, that's roughly $44M in non-cash amortization eating directly into GAAP net income every single year. This drag shrinks predictably over time as the intangible balances age down — it's mathematical, not operational.
The second is interest expense. Interest expense was $12.6 million for Q1 2026 — roughly $50M annualized — on the $758M term loan. That's real cash out the door to Citibank every quarter, and it flows directly through the income statement reducing taxable income and net income.
The third is that Karman is in a heavy investment phase right now. Roughly half of 2026 growth is inorganic, meaning integration costs, one-time transaction fees, and the setup costs of folding Seemann, ISP, and Metal Technology into the operating structure are all burdening the current GAAP P&L even as those acquisitions produce revenue.
By revenue segment, as of Q1 2026, the breakdown is: Tactical Missiles and Integrated Defense Systems 30%, Space and Launch 29%, Hypersonics and Strategic Missile Defense 24%, and Maritime Defense Systems 17%.
So defense — combining tactical missiles, hypersonics, and maritime — accounts for roughly 71% of revenue, and space is 29%. This is primarily a defense company.
- But the specific nature of its defense work is what matters: it's not in legacy platforms like aircraft or armored vehicles.
- It's in the fastest-growing segments of DoD spending: hypersonic weapons, missile defense interceptors, guided munitions, and UAS systems.
- These programs have strong bipartisan support and are explicitly protected in budget discussions.
----------
There was a secondary offering at $61/share in late May for original private equity owners to sell shares. I'm talking about Trive Capital, who brought the company public in 2025. KRMN was not able to receive any money from the sale and no new shares were issued. Good. This sale was Trive making a distribution to their investors.
The good news is that Trive is now largely out of the way with their current ownership at only 3% after selling 65% of their shares in that recent round.
So $54/share isn't bad IMO, especially given the price targets, guidance, and backlog.
I bought 115 shares because, in short, EPS is expected to improve tremendously due to a good cleaning up of the capital structure:
The first and biggest is intangible amortization. Every time Karman acquires a company, accounting rules require it to assign fair values to the acquired customer relationships, technology, backlog, and brand — and then amortize those values over their estimated useful lives, typically 7–15 years. Amortization rose to $10.9 million in Q1 2026 alone, with intangible assets now sitting at $400.5 million net on the balance sheet. Annualized, that's roughly $44M in non-cash amortization eating directly into GAAP net income every single year. This drag shrinks predictably over time as the intangible balances age down — it's mathematical, not operational.
The second is interest expense. Interest expense was $12.6 million for Q1 2026 — roughly $50M annualized — on the $758M term loan. That's real cash out the door to Citibank every quarter, and it flows directly through the income statement reducing taxable income and net income.
The third is that Karman is in a heavy investment phase right now. Roughly half of 2026 growth is inorganic, meaning integration costs, one-time transaction fees, and the setup costs of folding Seemann, ISP, and Metal Technology into the operating structure are all burdening the current GAAP P&L even as those acquisitions produce revenue.
Posted on 6/16/26 at 1:24 pm to bayoubengals88
Maybe this is finally making a turn.
Posted on 6/16/26 at 1:34 pm to BottomFeeder
I kept dumping for slight gain or loss.
It should damn well be bottomed.
Extremely low margin type of business though. Not really my cup of tea long term.
It should damn well be bottomed.
Extremely low margin type of business though. Not really my cup of tea long term.
Posted on 8/7/26 at 4:35 pm to bayoubengals88
There's a lot of good here. I think I'm finally long. Profit margins are set to start improving tremendously. Earnings were yesterday and they were pretty great. I acted at $52.90
I think this is a great company and it diversifies my portfolio without sacraficing too much growth.
I've come to learn that KRMN is very necessary for missile production.
KRMN — Karman Space & Defense
What the company is
- When Lockheed or RTX builds a missile or rocket, they don't make every part. They hand the hard structural pieces to specialists. Karman is one of those specialists.
- Its edge: once a Karman part is designed into a weapon and tested for years, switching to a rival costs the customer more than it's worth. That keeps competitors out.
What it makes
- Nose cones that protect the warhead or satellite
- The joints that connect and separate rocket stages
- Rocket motors and heat shields
Who buys it
- Hypersonics and missile defense — growing 18.7%, and where "Golden Dome" defense money is flowing
- Tactical missiles — steady demand, since every missile fired has to be replaced
- Space and launch — growing 29.5%, the fastest area
- No single program is more than 10% of sales, so it wins no matter which weapon or rocket succeeds
How it grows
- Around 20% a year on its own, plus roughly 10% from buying smaller firms
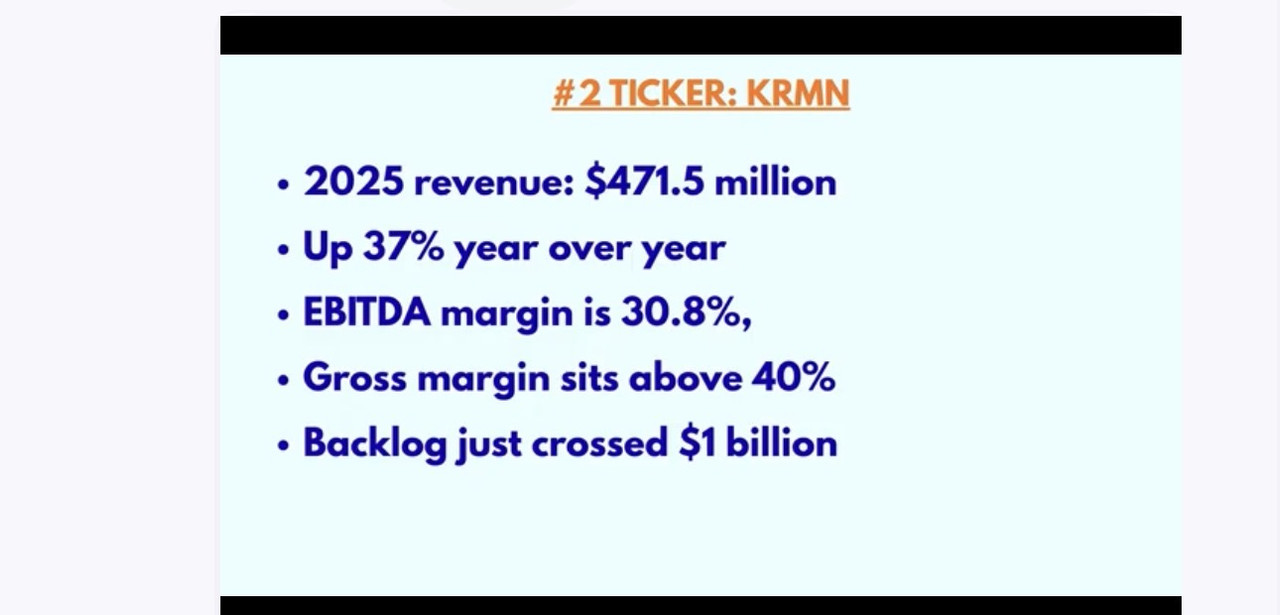
- Sales: $471M in 2025, guided to $720–735M in 2026
The profit picture
- It keeps about 31 cents of every sales dollar as operating profit — and that's held steady even as sales doubled
- But actual bottom-line profit is thin (under 4 cents per dollar) because interest on its debt eats most of it
- As it pays that debt down, more profit should reach the bottom line
Where it could go (5–10 years)
- Good case: $3–4B+ in sales, or bought out by a larger defense firm
- Middle case: $1.5–2B+, stock doubles or triples
- Bad case: defense budgets tighten, the stock drops 30% or goes nowhere
The main risks
- Expensive stock, meaningful debt, and its private-equity owner keeps selling shares, which can cap gains (later debunked)
- Its real value to a portfolio: it moves on defense spending, not the AI wave everything else rides

I think this is a great company and it diversifies my portfolio without sacraficing too much growth.
I've come to learn that KRMN is very necessary for missile production.
KRMN — Karman Space & Defense
What the company is
- When Lockheed or RTX builds a missile or rocket, they don't make every part. They hand the hard structural pieces to specialists. Karman is one of those specialists.
- Its edge: once a Karman part is designed into a weapon and tested for years, switching to a rival costs the customer more than it's worth. That keeps competitors out.
What it makes
- Nose cones that protect the warhead or satellite
- The joints that connect and separate rocket stages
- Rocket motors and heat shields
Who buys it
- Hypersonics and missile defense — growing 18.7%, and where "Golden Dome" defense money is flowing
- Tactical missiles — steady demand, since every missile fired has to be replaced
- Space and launch — growing 29.5%, the fastest area
- No single program is more than 10% of sales, so it wins no matter which weapon or rocket succeeds
How it grows
- Around 20% a year on its own, plus roughly 10% from buying smaller firms
- Sales: $471M in 2025, guided to $720–735M in 2026
The profit picture
- It keeps about 31 cents of every sales dollar as operating profit — and that's held steady even as sales doubled
- But actual bottom-line profit is thin (under 4 cents per dollar) because interest on its debt eats most of it
- As it pays that debt down, more profit should reach the bottom line
Where it could go (5–10 years)
- Good case: $3–4B+ in sales, or bought out by a larger defense firm
- Middle case: $1.5–2B+, stock doubles or triples
- Bad case: defense budgets tighten, the stock drops 30% or goes nowhere
The main risks
- Expensive stock, meaningful debt, and its private-equity owner keeps selling shares, which can cap gains (later debunked)
- Its real value to a portfolio: it moves on defense spending, not the AI wave everything else rides
Posted on 8/8/26 at 5:48 pm to LChama
I really think this company deserves a weekend look after Q2 earnings.
Posted on 8/9/26 at 4:22 am to bayoubengals88
In for a few shares.
Posted on 8/9/26 at 6:31 am to LChama
KRMN is not PLTR. What a terrible comparison. But it’s likely a good value
Posted on 8/9/26 at 7:46 am to Upperdecker
Karman will benefit from this.
Missile Shortage
That’s the business…
Missile Shortage
quote:
Bombing Iran burned through thousands of multimillion-dollar missiles that contain precision parts from a global web of suppliers and can take years to produce.
That’s the business…
This post was edited on 8/9/26 at 7:50 am
Posted on 8/14/26 at 2:43 pm to LChama
One of the prettiest setups you'll ever see.
If it bases above the 200 day at 73.60 that's yet more confirmation of a continued uptrend.

If it bases above the 200 day at 73.60 that's yet more confirmation of a continued uptrend.
 Page 1 of 1

Popular
Back to top
 Follow TigerDroppings for LSU Football News