- My Forums
- Tiger Rant
- LSU Recruiting
- SEC Rant
- Saints Talk
- Pelicans Talk
- More Sports Board
- Fantasy Sports
- Golf Board
- Soccer Board
- O-T Lounge
- Tech Board
- Home/Garden Board
- Outdoor Board
- Health/Fitness Board
- Movie/TV Board
- Book Board
- Music Board
- Political Talk
- Money Talk
- Fark Board
- Gaming Board
- Travel Board
- Food/Drink Board
- Ticket Exchange
- TD Help Board
Customize My Forums- View All Forums
- Topic Sort Options
- Trending Topics
- Recent Topics
- Active Topics

TorchtheFlyingTiger
| Favorite team: | North Carolina St.  |
| Location: | 1st coast |
| Biography: | |
| Interests: | LSU & NC St sports, travel, finance |
| Occupation: | FIRE'd |
| Number of Posts: | 3408 |
| Registered on: | 1/14/2008 |
| Online Status: | Not Online |
Recent Posts
Message
re: Anybody Transferred their IRA to Robinhood for the 2% Bonus?
Posted by TorchtheFlyingTiger on 10/6/26 at 12:53 am to TigerDeBaiter
It doesn't count towards your contribution limit.

 0

re: Anybody Transferred their IRA to Robinhood for the 2% Bonus?
Posted by TorchtheFlyingTiger on 10/5/26 at 4:07 pm to Skippy1013
I took their bonus $ ($27k so far) and have had no issues. I just buy and hold index funds so don't see how their past trading pause issues could effect me. They have same SIPC protections as other brokerages. Only thing I really don't like is they encourage users to play predictions markets including sports. I'd avoid the platform if susceptible to gambling. Their interface is also kinda cheesy to me but some like it and think it's more enjoyable
For all their faults, RH helped bring zero fee trades to the consumer investor and it's now industry standard. Others can keep hating them, I'll keep taking the company's money.
For all their faults, RH helped bring zero fee trades to the consumer investor and it's now industry standard. Others can keep hating them, I'll keep taking the company's money.
re: Dumb f**ks that scream “tax the rich more!”
Posted by TorchtheFlyingTiger on 10/4/26 at 1:08 pm to doubleb
quote:If they exceed annual gift limits it just comes off their lifetime exclusion.
it would be extremely hard for both parents to give their kid 2 million plus dollars by the time he is in his late twenties
I'm for low taxes but the thing that makes no sense to me is the stepped up cost basis at death. Why do I pay tax on my investments if I sell but my heirs don't if they sell? I'm planning to use this to full advantage for my heirs but seems like a reasonable thing to change.
re: Trump administration announced 2B worth of checks direct to seniors
Posted by TorchtheFlyingTiger on 10/3/26 at 10:47 am to UltimaParadox
Sadly, there is no fiscally responsible party.
re: 175 mph tire blowout in a Tesla model S on the autobahn
Posted by TorchtheFlyingTiger on 10/1/26 at 1:19 pm to tigeraddict
According to the video title and notes he was running tires that are recalled for tread delamination. Wonder if this was before or after the recall went out.
Goodyear Eagle F1 SuperSport 305/30ZR21
Speed rating Y = 300 km/h
(recalled for Tread Delamination)
Goodyear Eagle F1 SuperSport 305/30ZR21
Speed rating Y = 300 km/h
(recalled for Tread Delamination)
re: Paying off debt strategy
Posted by TorchtheFlyingTiger on 9/30/26 at 3:54 pm to KTiger85
I went a step further and borrowed against my investment portfolio to fund my current home down payment.
At first I was paying down the loan balance and interest. Past couple years, I've just been letting interest accrue an not making any payments. Seeing those investments grow much faster than the loan balance hits different. (Plus heirs wont have to pay tax on all these gains) The first home we ever bought, we paid off early. It didnt feel this good.
At first I was paying down the loan balance and interest. Past couple years, I've just been letting interest accrue an not making any payments. Seeing those investments grow much faster than the loan balance hits different. (Plus heirs wont have to pay tax on all these gains) The first home we ever bought, we paid off early. It didnt feel this good.

re: Paying off debt strategy
Posted by TorchtheFlyingTiger on 9/29/26 at 11:20 am to REB BEER
This episode?
If had seen his question on X, I would have been one of those rare replies that regret paying off mortgage. I aggressively paid down my first home at 5.5%. If I'd have invested it instead I'd be much better off. It easily cost me 6 figures in missed growth. Opportunity cost is a bitch.
If had seen his question on X, I would have been one of those rare replies that regret paying off mortgage. I aggressively paid down my first home at 5.5%. If I'd have invested it instead I'd be much better off. It easily cost me 6 figures in missed growth. Opportunity cost is a bitch.
re: Paying off debt strategy
Posted by TorchtheFlyingTiger on 9/29/26 at 11:18 am to geauxtigers
Agreed, don't buy unnecessary depreciating assets you can't afford. Especially if you're early in accumulation phase it can really set you back. However, if you are buying out of necessity or even enjoyment within reason, there's no reason to avoid low interest debt.
For instance, I am fully invested. I WANT a Tesla. Why sell shares and realize 15% LTCG when I can borrow at 1.5% dealer incentive rate? Sure, I could wait and save cash but that would just be deferring further investment in appreciating assets. Instead, I'll benefit from the interest rate arbitrage.
For instance, I am fully invested. I WANT a Tesla. Why sell shares and realize 15% LTCG when I can borrow at 1.5% dealer incentive rate? Sure, I could wait and save cash but that would just be deferring further investment in appreciating assets. Instead, I'll benefit from the interest rate arbitrage.
re: Paying off debt strategy
Posted by TorchtheFlyingTiger on 9/29/26 at 10:45 am to Suntiger
quote:
Vehicles are a depreciating asset, so those should probably be paid off as well,
quote:I've never quite understood this concept. How does it matter whether or not the asset appreciates? If you NEED the vehicle or can afford it, why not take out low interest debt to fund the purchase and keep more $ invested in appreciating assets? What's different about paying down a depreciating asset debt versus one that appreciates? Assuming same rate, I'd make the case that paying down car loan is better than mortgage because the car can be sold easily making it a more liquid asset instead of tieing up your capital in home equity for decades (expensive to access via HELOC or sale)
don't go in debt for depreciating assets pay cash
re: Paying off debt strategy
Posted by TorchtheFlyingTiger on 9/29/26 at 9:44 am to AUVet21
I'm all for paying off and avoiding unnecessary debt. Rates still matter though. Are these sub 4% rates? If so, I'd be in no rush to pay off and would rather fully fund tax advantaged investments first.
Also, depends on how financially secure you are. Is emergency fund robust, job extremely stable? If not, keeping the cash in a HYSA until you have enough to pay off a debt in full and free up the payment could be best approach.
Also, depends on how financially secure you are. Is emergency fund robust, job extremely stable? If not, keeping the cash in a HYSA until you have enough to pay off a debt in full and free up the payment could be best approach.
re: And Now for Something Completely Different from the modeling desk
Posted by TorchtheFlyingTiger on 9/26/26 at 4:14 pm to choppadocta
I came here for the Monty Python.
re: Do you decorate more for Halloween or Christmas?
Posted by TorchtheFlyingTiger on 9/25/26 at 12:07 pm to LSU Coyote
Halloween obsessed people are creeps. Had some folks with decorations up first week of Sept. When did a kid focused 1 day holiday become a 2 month event primarily for adults more than trick or treaters?
Seems super weird to be into the Halloween theme for weeks on end. Go all out if you like, it's fun for a few days maybe even a full month but I prefer not to see huge yard skeletons for 2 months.
Seems super weird to be into the Halloween theme for weeks on end. Go all out if you like, it's fun for a few days maybe even a full month but I prefer not to see huge yard skeletons for 2 months.
re: I don't see how the restaurant industry can survive in its current format.
Posted by TorchtheFlyingTiger on 9/25/26 at 10:30 am to Billy Blanks
There's some good value to be had at some chains. The Chili's 3 for me and BW3s pick 6 deals are better price and quality than fast food meals.
re: I don't see how the restaurant industry can survive in its current format.
Posted by TorchtheFlyingTiger on 9/25/26 at 8:39 am to Cotten
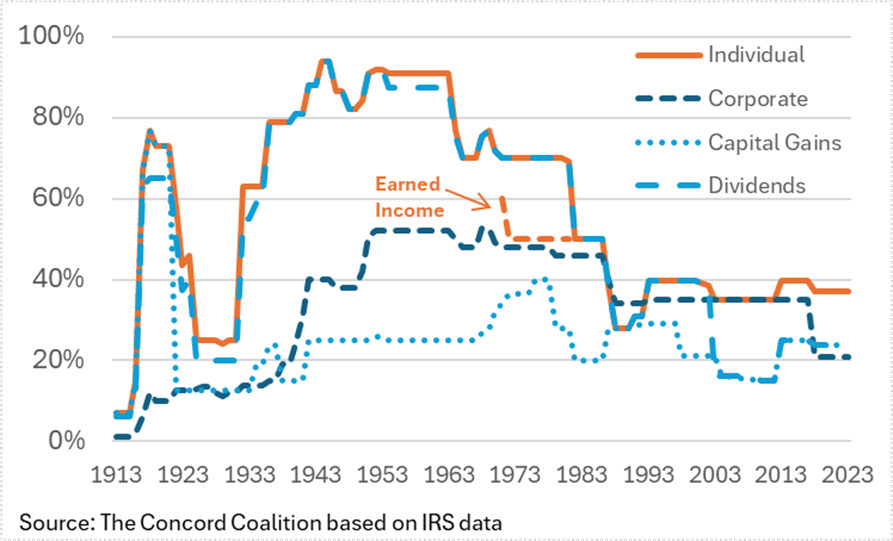
It's not higher taxes. I'm still all for bringing taxes down further and cutting government spending, fraud and waste.
re: I don't see how the restaurant industry can survive in its current format.
Posted by TorchtheFlyingTiger on 9/25/26 at 8:30 am to theliontamer
re: I don't see how the restaurant industry can survive in its current format.
Posted by TorchtheFlyingTiger on 9/25/26 at 8:26 am to theliontamer
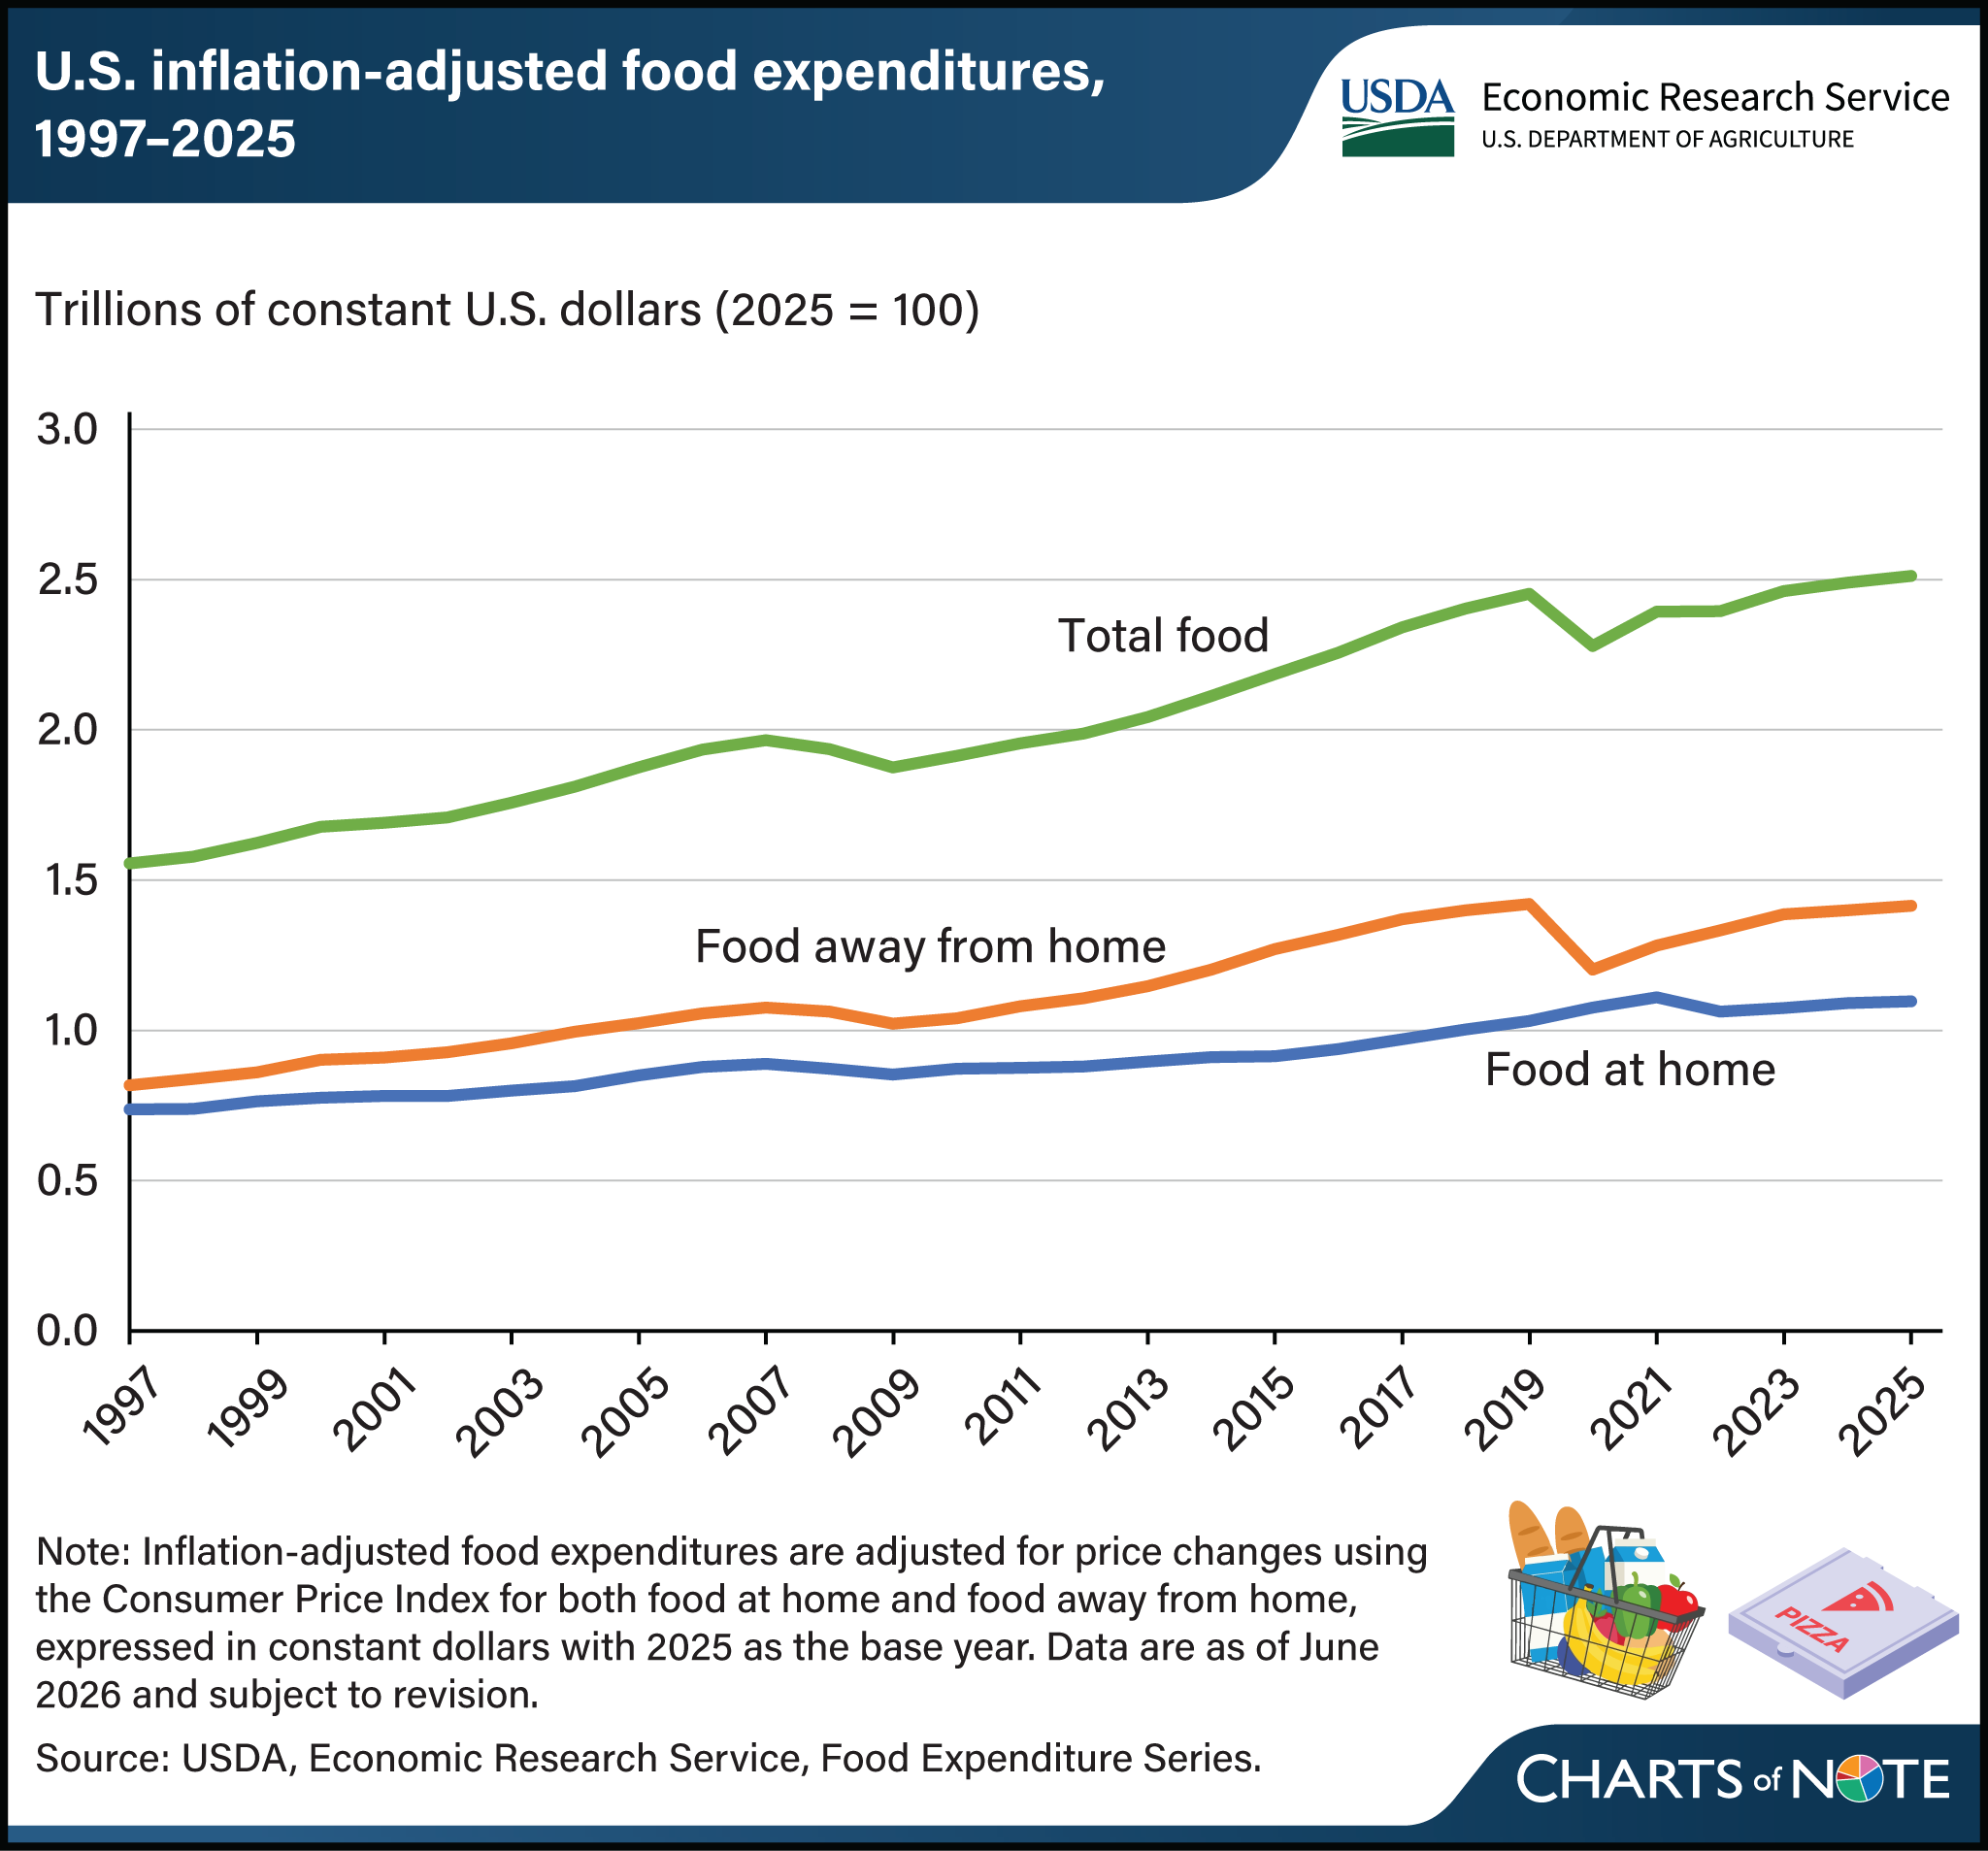
People eat out or order delivery more nowadays. What used to be a special treat is nearly every meal out for a growing segment of population. Its shocking how some folks dont cook much at all.
Taxes arent higher. We are in a comparatively low tax era.
Some off yall just make up this sky is falling shite and then others echo it.
Always been a tough high failure business.
Taxes arent higher. We are in a comparatively low tax era.
Some off yall just make up this sky is falling shite and then others echo it.
Always been a tough high failure business.
re: Karl Bushby soon to complete 28 year long walk from Chile to England
Posted by TorchtheFlyingTiger on 9/24/26 at 11:21 am to bountyhunter
My first reaction was to hate him for being an absentee father. On further reading, sounds like he was possibly trying to cope with losing the kid etc. His wife reportedly took the child back to N. Ireland where they met while he was a British paratrooper. Due to security restrictions he was unable to visit as an active duty member. However, he left service a year or two later perhaps he could have followed them at that point. Perhaps he knew it was best to stay away. He's obviously not a normal person and no telling what other issues they both may have had. Apparently the kid joined him at some point along the road and they bonded for a couple weeks, small consulation for a fatherless childhood.
re: What was your final straw or main reason you left Louisiana?
Posted by TorchtheFlyingTiger on 9/22/26 at 7:46 pm to DatGuy6967
Closure of England Air Force Base.
re: Can someone school me on FICO?
Posted by TorchtheFlyingTiger on 9/22/26 at 6:33 am to bayoubengals88
Meanwhile,
Same link further down has article with more bullish take: "FICO Stock Has Fallen 43% From Its Peak. Does the Selloff Make Sense?"
quote:finance.yahoo.com
The Federal Housing Finance Agency has shaken up Fair Isaac (FICO) by allowing Fannie Mae and Freddie Mac to accept VantageScore 4.0, ending FICO's exclusive role in government backed mortgage credit scoring.
Same link further down has article with more bullish take: "FICO Stock Has Fallen 43% From Its Peak. Does the Selloff Make Sense?"
quote:
The Business Kept Growing While the Stock Fell
The economics of FICO's model are genuinely unusual, and understanding them is what makes the 2026 selloff so interesting. An 85% gross margin means almost every revenue dollar above the marginal cost of delivering a score flows straight through to gross profit.
re: Can someone school me on FICO?
Posted by TorchtheFlyingTiger on 9/22/26 at 6:23 am to bayoubengals88
I heard about this on CNBC last week. They've aggressively increased
prices leading some customers to seek other methods.
2023: FICO implemented a steep tier-based structure ranging from $0.60 to $2.75 per score (spiking costs up to 400% for some).
2024: FICO shifted to a fixed royalty of $3.50 per score after receiving heavy industry pushback.
2025: FICO raised the price further to $4.95 per score.
2026: FICO doubled prices again up to $10.00 for certain traditional mortgage reporting channels while introducing direct-licensing alternatives
re: Looking for some advice (Investing)
Posted by TorchtheFlyingTiger on 9/21/26 at 9:18 pm to 3D
quote:You're way off.
similar but not exactly the same
"SCHD and SCHG have virtually zero overlap (less than 1% by weight), making them nearly perfect polar opposites.Because of their strict and contrasting selection criteria, these two ETFs share almost no common holdings. SCHG filters for high-growth companies that reinvest all their cash, while SCHD strictly selects stable, cash-flowing companies with a track record of paying high dividends." -Google AI mode
Popular
 29