




 1


- My Forums
- Tiger Rant
- LSU Recruiting
- SEC Rant
- Saints Talk
- Pelicans Talk
- More Sports Board
- Fantasy Sports
- Golf Board
- Soccer Board
- O-T Lounge
- Tech Board
- Home/Garden Board
- Outdoor Board
- Health/Fitness Board
- Movie/TV Board
- Book Board
- Music Board
- Political Talk
- Money Talk
- Fark Board
- Gaming Board
- Travel Board
- Food/Drink Board
- Ticket Exchange
- TD Help Board
Customize My Forums- View All Forums
- Show Left Links
- Topic Sort Options
- Trending Topics
- Recent Topics
- Active Topics
Started By
Message
Did I stumble into something interesting?? IDN options
Posted on 9/24/26 at 12:49 pm
Posted on 9/24/26 at 12:49 pm
Intellicheck (IDN) is a micro cap identity verification company (48 million market cap)
They validate government-issued IDs in real time, immediately telling banks, stadiums, auto dealers, and freight companies whether a license is genuine or a sophisticated fake.
The business itself is pristine: 91% gross margins, zero debt, $11.8M cash, profitable four consecutive quarters, growing 16% year over year.
Trading at 4x cash and 2x sales with a P/E of 15...
AI-generated fraud is only getting worse. The theme couldn't be more relevant.
Part I
The stock fell 74% — from $9 to $2.36 — because one customer representing 29% of first-half revenue is reviewing its vendor strategy following a merger. Management guided revenue "slightly below" 2025 levels. Not catastrophically below. Slightly. The market priced near-complete customer loss on a partial-reduction warning. Someone overreacted.
That's interesting enough on its own.
BUT...
Part II
Two days ago, someone bought 1,500 February 2027 $3 calls at $0.34.
That's nearly $52,000 committed on a $47M micro-cap with zero prior open interest on that strike.
They didn't follow anyone into this trade.
They created the market out of thin air.
On a stock this illiquid, 1,500 contracts can't be quietly sold off.
The spreads would punish any attempted exit.
Whoever did this intends to hold to a specific outcome, likely through both the November and February earnings prints.
That is not a casual bet.
That is someone who did the work and sized up knowing they're committed.
Three explanations:
- whoever bought those calls already knows the customer is staying
- the 74% drop is simply too much punishment for a partial revenue dip and someone did the math
- a larger identity verification company looks at this balance sheet — zero debt, $11.8M cash — and writes a check.
This may be nothing, but does it seem like nothing?
I'm certainly interested in the theme and the company going forward.
TLDR: Micro cap ID verification company. Pristine financials. One customer spooked the market into a 74% selloff. Three days ago someone dropped $51K on February calls with zero prior open interest on that strike — creating the market from scratch with no easy exit. Either the customer stays, the math is obvious, or someone's about to buy the whole company.
They validate government-issued IDs in real time, immediately telling banks, stadiums, auto dealers, and freight companies whether a license is genuine or a sophisticated fake.
The business itself is pristine: 91% gross margins, zero debt, $11.8M cash, profitable four consecutive quarters, growing 16% year over year.
Trading at 4x cash and 2x sales with a P/E of 15...
AI-generated fraud is only getting worse. The theme couldn't be more relevant.
Part I
The stock fell 74% — from $9 to $2.36 — because one customer representing 29% of first-half revenue is reviewing its vendor strategy following a merger. Management guided revenue "slightly below" 2025 levels. Not catastrophically below. Slightly. The market priced near-complete customer loss on a partial-reduction warning. Someone overreacted.
That's interesting enough on its own.
BUT...
Part II
Two days ago, someone bought 1,500 February 2027 $3 calls at $0.34.
That's nearly $52,000 committed on a $47M micro-cap with zero prior open interest on that strike.
They didn't follow anyone into this trade.
They created the market out of thin air.
On a stock this illiquid, 1,500 contracts can't be quietly sold off.
The spreads would punish any attempted exit.
Whoever did this intends to hold to a specific outcome, likely through both the November and February earnings prints.
That is not a casual bet.
That is someone who did the work and sized up knowing they're committed.
Three explanations:
- whoever bought those calls already knows the customer is staying
- the 74% drop is simply too much punishment for a partial revenue dip and someone did the math
- a larger identity verification company looks at this balance sheet — zero debt, $11.8M cash — and writes a check.
quote:
I tailed the calls and bought some $2 strikes for next May.
It may be a nice play just to buy the stock.
I promise not to dump these options on you if you buy them. Seriously. I wouldn't do that.
This may be nothing, but does it seem like nothing?
I'm certainly interested in the theme and the company going forward.
TLDR: Micro cap ID verification company. Pristine financials. One customer spooked the market into a 74% selloff. Three days ago someone dropped $51K on February calls with zero prior open interest on that strike — creating the market from scratch with no easy exit. Either the customer stays, the math is obvious, or someone's about to buy the whole company.
Posted on 9/24/26 at 2:54 pm to bayoubengals88
Thank you, bayoubengals88.
From an April 9th analysis on SA, FWIW:
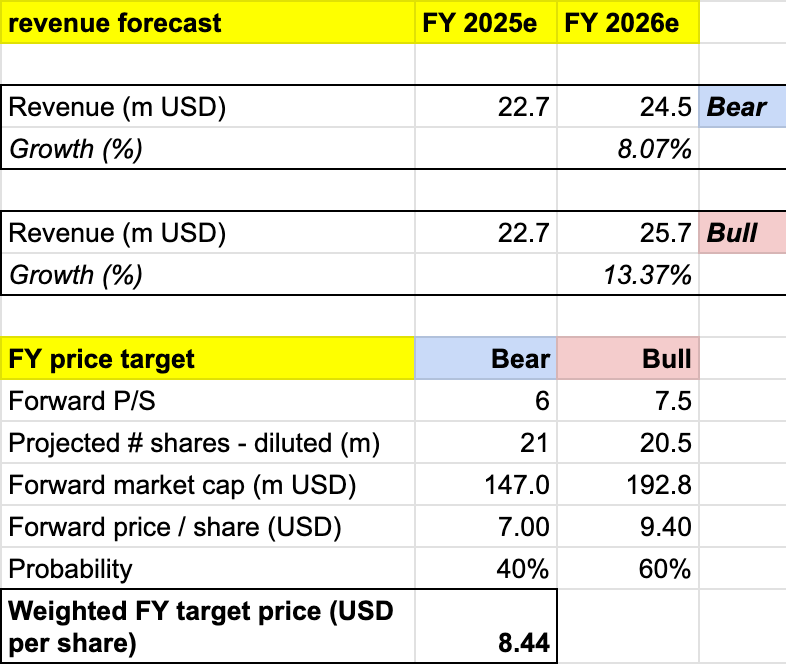
From an April 9th analysis on SA, FWIW:
quote:
DN achieved double-digit revenue growth, GAAP profitability, and strong operating cash flow in FY 2025, signaling a shift to a self-sustaining business model.
Catalysts for 2026 include robust demand in financial services and retail, driven by escalating identity fraud threats and expansion into new verticals.
Risks center on high revenue concentration—the top ten customers account for 77% of revenue—and recent share price momentum possibly signaling a near-term top.
quote:
I believe catalysts into 2026 would be quite strong for IDN. I think, given the positive turning point we have seen in FY 2025 with double-digit revenue growth, positive GAAP profitability, as well as strong OCF generation, the key question would be, can IDN sustain that kind of performance into the new FY?
So far, I believe there are two forces to evaluate to understand if IDN could deliver as expected. The first one is the favorable macro landscape in IDN’s key verticals, financial services and retail, which the management believes could help sustain demand
Based on my experience covering other identity verification or security-related stocks, I do think that the overall macro trends indeed are favorable for IDN, especially with the rise of generative AI (GenAI) technology that could elevate the risk level in identity verification, primarily in financial services.
quote:
Risk is moderate overall, in my opinion. One important thing I found is that IDN seems to have a deep revenue concentration on its top ten customers, as per its 10-K:
For the fiscal years ended December 31, 2025 and 2024, our top ten customers accounted for approximately 77% and 71% of our total revenues, respectively. The loss of any one of these significant customers, or a reduction in their spending levels, could have a material adverse effect on our business, financial condition, and results of operations.
quote:
My 1-year target price for IDN is driven by the following assumptions for the bull vs. bear scenarios, based on consensus estimate:
Bull scenario (60% probability) assumptions - I project IDN to deliver a revenue at the high end of the consensus estimate, with the demand environment continuing to strengthen and IDN successfully scaling its banking and lending as well as automotive verticals, followed by solid margin expansions from disciplined cost management. This should help drive re-rating to 7.5x P/S, a valuation premium for IDN.
Bear scenario (40% probability) assumptions - I project some slowdown happening in mid-2026 that does affect some of IDN's client base, delaying contract signing, transactions, and potential renewal discussions. In this situation, I would assume the market would price in the revenue concentration risk, meaning that IDN sees a 6x P/S, just slightly lower than its TTM P/S today, indicating a correction.
 Page 1 of 1

Popular

Back to top
 Follow TigerDroppings for LSU Football News